


India-China electronics supply chain ties are showing an unexpected shift. India’s exports to China rose nearly 40% in the first five months of FY27, with electronics and engineering goods accounting for a significant part of the increase. The numbers remain modest and require careful interpretation, but they point to a possibility that would have seemed unlikely in the older trade narrative: Indian factories may be beginning to supply selected intermediate electronics to China’s vast manufacturing ecosystem.
For decades, the dominant pattern was straightforward. India imported components, machinery and finished goods from China, assembled some products domestically and exported others to third markets. China supplied the upstream depth, supplier networks and production scale that Indian industry had not yet developed. The latest data does not overturn that relationship. India imported $131.6 billion of Chinese goods in FY26 while exporting approximately $19.5 billion, leaving a bilateral deficit of about $112 billion.
What is changing is the direction of some manufacturing flows within that larger imbalance. India’s exports to China increased by 39% in the first five months of FY27, according to the data cited by Economic Times. Electronics and engineering goods were among the main drivers. The increase came from a low base and has been linked by industry representatives to demand associated with artificial intelligence infrastructure and data-centre construction. But the deeper story is not simply that China bought more Indian goods during an AI-related investment cycle. It is that India may now have enough manufacturing capacity to participate in selected stages of China-centred production.
## The PCBA signal
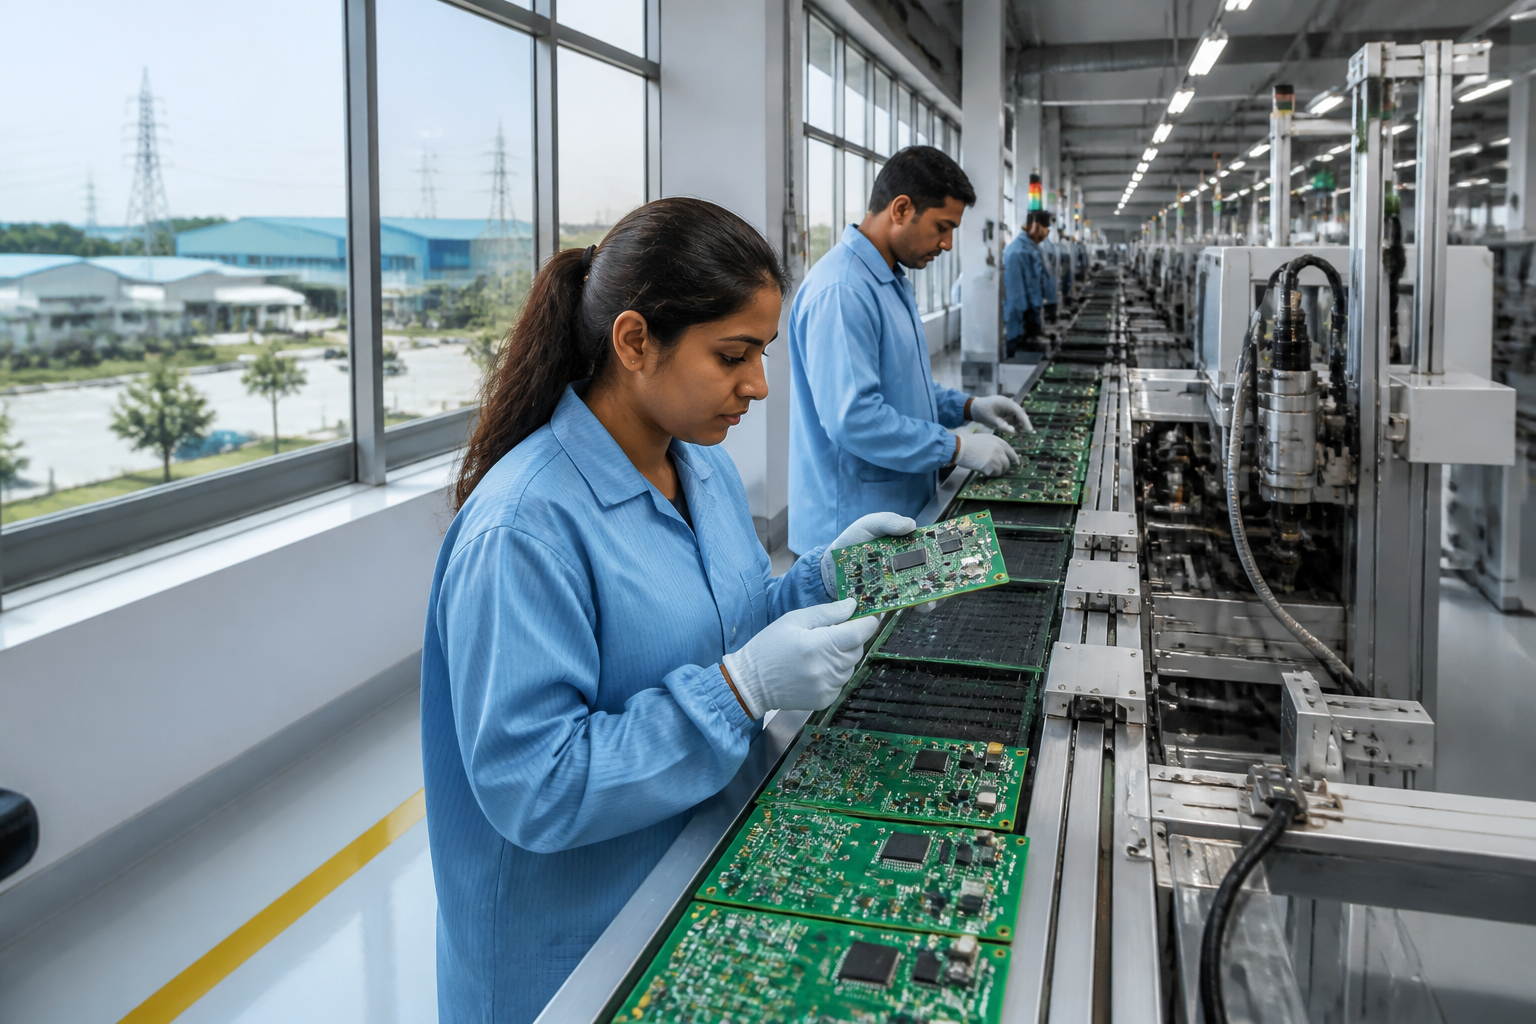
One of the clearest indicators is the movement in printed circuit board assembly exports. India’s PCBA exports to China rose more than 40-fold in FY26, reaching $1.5 billion from $36 million a year earlier. Nearly 80% of India’s total PCBA exports went to China. Overall Indian PCBA exports increased more than 20-fold to $1.9 billion.
These figures are significant because PCBAs sit between bare circuit boards and more complex finished electronic products. They are an intermediate manufacturing stage rather than a complete electronics ecosystem. Their rise suggests that Chinese manufacturers may be sourcing relatively simpler assemblies from India while concentrating more of their own production capacity on sophisticated components, systems and products.
The data, however, is not perfectly clean. Chinese customs figures do not show a matching increase in PCB imports from India, and some of the reported trade may have been classified under smartphones or telecom equipment. Differences in customs classification make it difficult to determine precisely which products are moving and how much of the increase represents PCBAs in the strict sense.
That limitation matters. The evidence does not establish that China is transferring low-end manufacturing to India or that Indian suppliers are replacing Chinese manufacturers. It does establish that electronics exports from India to China have expanded sharply in some categories, while the precise composition of that trade remains partly obscured by classification differences.
## China is moving up, India is building out
The possible shift becomes more understandable when the two manufacturing systems are viewed together. China’s industrial advantage is no longer based only on producing inexpensive goods. It has built a dense network of suppliers that allows factories to divide production into increasingly specialised stages. As Chinese companies move into semiconductors, advanced electronics, AI servers and telecom equipment, they may not need to retain every relatively simple sub-assembly inside the country if it can be sourced competitively elsewhere.
That is where India could fit—not by recreating China’s entire industrial ecosystem, but by becoming competitive in selected intermediate products. India’s electronics manufacturing services sector remains concentrated in PCBA and basic box-build manufacturing. Design-led manufacturing and more sophisticated electronics are at an earlier stage. This creates a narrow but plausible role for Indian firms inside broader Asian production networks.
The opportunity is linked to capacity that India has been building for several years. Electronics production increased from Rs 1.9 lakh crore in 2014-15 to Rs 13.11 lakh crore in 2025-26, according to government data cited in the report. Electronics exports rose from approximately Rs 38,000 crore to Rs 4.24 lakh crore during the same period.
The increase reflects smartphone assembly, production-linked incentives, contract manufacturing and the expansion of electronics manufacturing services. The next stage of policy is aimed at components, sub-assemblies, materials and equipment rather than only finished-device assembly.
The Electronics Components Manufacturing Scheme is central to that transition. Its allocation was increased from Rs 22,919 crore to Rs 40,000 crore. By August, 106 projects involving Rs 69,548 crore of investment had been approved, with 38 plants either operational or in advanced stages of construction. The stated policy objective is to increase domestic capacity in components and raw materials. That is also the type of capacity that could eventually produce goods for export to China.
## An industrial ecosystem, not self-sufficiency
The apparent contradiction at the heart of India’s electronics story is that rising exports are occurring alongside high dependence on Chinese inputs. Domestic value addition remains around 18-20%. China supplied at least 80% of India’s imports across 71 electronics product lines in FY26, according to a study by the Koan Advisory Group and the Institute of Chinese Studies. The number of such product lines increased from 44 in 2018-19.
This means India is not yet replacing China. Indian factories can be exporting assemblies to China while importing a large share of the components, machinery and materials needed to make those assemblies. In an economy entering global value chains, that is not necessarily a contradiction. Production is often divided across countries according to cost, capability, scale and specialisation.
The emerging arrangement could therefore be more accurately described as two-way integration. China supplies sophisticated upstream components, machinery and production inputs. Indian manufacturers carry out selected assembly or component production. Some of those products then return to China for incorporation into more complex goods or are routed into wider global supply chains.
The model is different from the idea of complete domestic self-sufficiency. It also differs from the assumption that reducing dependence on China requires severing industrial links with Chinese suppliers. The data cited in the report suggests that India’s electronics industry may be becoming more deeply integrated with China even as policymakers seek to increase domestic value addition.
This is a particularly important distinction for manufacturing cities and industrial corridors. Expanding electronics capacity requires more than factory buildings. It depends on reliable power, logistics, industrial land, testing facilities, skilled labour, supplier parks and predictable approvals. As component manufacturing expands, the quality of these urban and industrial systems will determine whether India can move beyond assembly into repeatable, export-oriented production.
## AI demand is a catalyst, not the whole explanation
Artificial intelligence and data-centre construction have provided a powerful new source of demand for servers, networking equipment and related electronics. Industry representatives have linked part of the recent export increase to this build-out. Yet AI demand alone does not explain why Indian companies are now able to supply Chinese buyers.
The underlying capacity was accumulated through smartphone manufacturing, production-linked incentives, contract manufacturing and the more recent push into components. AI may have brought a large new market to Indian manufacturers at the moment when their production scale and capabilities began to improve.
That distinction is important because some AI-related demand may be cyclical. If investment in AI infrastructure slows, a portion of the current export growth could weaken. But factories, supplier relationships, production know-how and customer certifications are not immediately erased when one demand cycle changes. An Indian manufacturer that becomes an approved supplier to a major electronics company may gain access to additional products and markets.
The durability of the trend will depend on whether exports to China broaden beyond assembled electronics. The next test will be components such as more sophisticated boards, connectors, camera modules, displays, passive components, materials and other industrial inputs. The supplied evidence does not yet establish that this broader shift has occurred, but it identifies the direction in which the policy and industry push is moving.
## The policy challenge is depth
India’s policy challenge is no longer only to attract large assembly plants. It is to create the industrial depth that allows those plants to source more inputs locally and supply multiple markets. The expansion of the Electronics Components Manufacturing Scheme reflects that change in emphasis.
The Commerce Department has described global electronics production as increasingly organised around global value chains and has stressed the need for a predictable policy environment. That requirement extends beyond incentives. Manufacturers need continuity in tariff structures, approvals, infrastructure delivery, logistics and standards. Component ecosystems also require enough scale for specialised suppliers to survive.
The trade data shows both progress and vulnerability. Electronics production and exports have expanded dramatically over the past decade, but domestic value addition remains limited and dependence on Chinese inputs is still substantial. A policy that focuses only on headline export value could therefore miss the more important question: how much of the production chain is actually being built in India?
For China, sourcing selected intermediate goods from India would not necessarily represent a strategic relocation of its manufacturing base. The evidence supplied does not support that conclusion. China’s domestic supplier ecosystem remains extensive, and the report notes that companies seeking to move production away from China continue to face difficulties involving supplier depth, skilled labour and factory infrastructure.
Outsourcing selected stages is a different proposition from relocating an entire industry. That distinction makes the possible trend more credible, but also more limited. India may not need to displace China in advanced electronics to gain a role in the supply chain. It may first need to become reliable and competitive in a narrower group of intermediate products.
The immediate trade figures are therefore less important than what they reveal about industrial positioning. India’s electronics sector is still dependent on Chinese inputs, but it may be moving from being only a destination for Chinese components to also becoming a supplier of selected assemblies and parts. Whether that becomes a durable two-way supply chain will depend on the next phase of component investment, the depth of domestic value addition and the ability of Indian industrial locations to support consistent, high-quality production.
The evidence confirms an emerging possibility, not a completed transformation. India-China trade remains heavily imbalanced, the absolute value of several export categories is still modest, and customs classifications complicate interpretation. The developments to monitor are whether exports to China continue rising, whether they broaden into more sophisticated components and whether the new capacity created under the components manufacturing policy achieves sustained domestic and international demand.
