


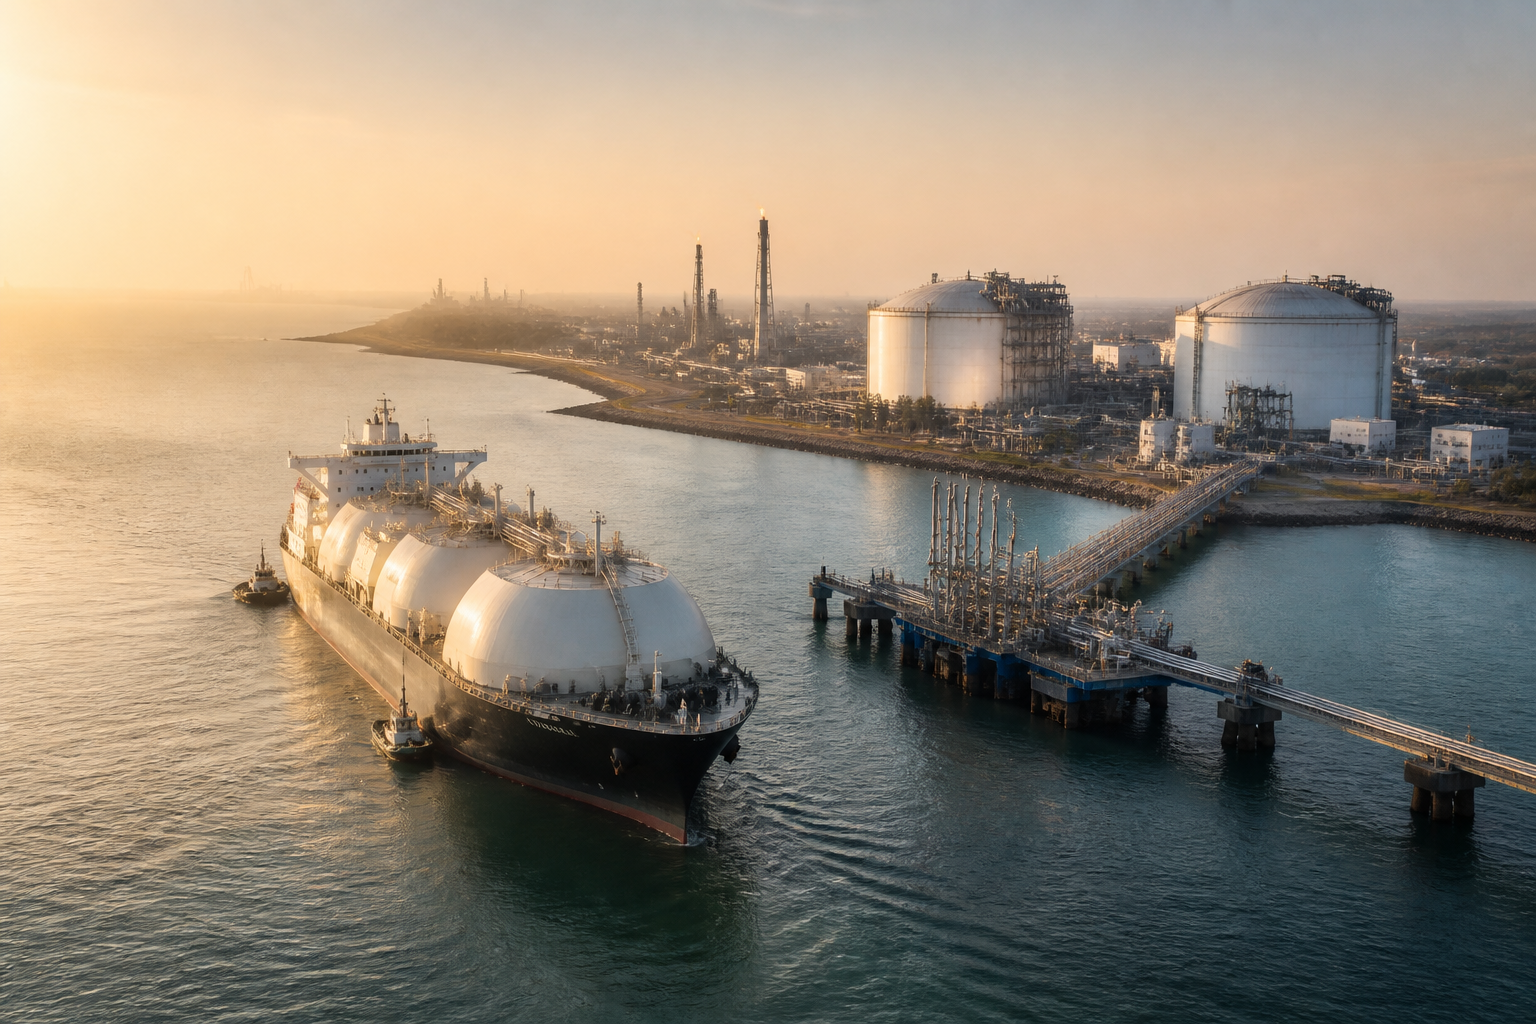
Chevron’s interest in securing an India LNG deal comes at a time when energy buyers are reassessing how they obtain gas, but the company’s own comments show why India may be a difficult market for portfolio suppliers: the opportunity is real, yet pricing remains the decisive test.
Freeman Shaheen, Chevron’s president of global gas, said in an interview on the sidelines of the Gastech conference in Bangkok that the company would like to reach an agreement in India. He also said Indian buyers were “very, very headline-price driven” and that the market was still evolving. No deal, buyer or delivery schedule was identified.
The significance of the statement lies less in an immediate commercial announcement than in the supply strategy behind it. Chevron is seeking to expand its global gas portfolio across Argentina, the East Mediterranean, Australia and Africa as buyers look for greater protection against disruptions affecting major producing regions. India, with its expanding role as an LNG market, is part of that opportunity, but the company’s comments make clear that access will depend on whether long-term supply can compete with the price expectations of importers.
The result is a familiar tension in LNG markets: buyers want security, flexibility and dependable delivery, while suppliers need contracts and prices that justify large, capital-intensive projects. The balance between those requirements will shape whether Chevron’s interest in India becomes a commercial agreement or remains an expression of future intent.
## A portfolio built around diversification
Chevron currently expects to have about 20 million metric tonnes per annum of LNG supply capacity. This comprises 16 million tonnes of net gas production from its projects and 4 million tonnes contracted from the US Gulf Coast. The US Gulf Coast volumes began in February and are expected to ramp up over the next few years in line with existing agreements.
Shaheen said Chevron wanted to continue expanding that portfolio. Argentina was identified as a promising market because of its crude and gas development, while the East Mediterranean was described as another attractive area. The company is also evaluating opportunities in Australia and Africa, subject to suitable capital, fiscal and regulatory conditions.
That approach reflects a shift away from dependence on any one producing region or contracting structure. According to the report, global gas markets have experienced two major disruptions in the past four years: the war in Ukraine in 2022 and the Iran conflict this year. The disruptions affected supplies from major producers, including Russia and Qatar, and pushed LNG prices higher.
Shaheen said the recent crisis reinforced the need for diversity in both supply sources and contracting structures. He also cautioned against relying on a spot market that is not as liquid as the markets for crude and petroleum products. For buyers, the implication is that a diversified supply portfolio may reduce exposure to a single disruption, but obtaining that protection may require commitments that are more expensive or less flexible than spot purchases when prices fall.
## Why India is an important but difficult market
Chevron’s interest in India is not accompanied by a specific project announcement. The company did not disclose a proposed partner, import terminal, contract volume, delivery point or start date. That absence matters because an LNG agreement requires more than a producer’s willingness to sell. It also depends on the buyer’s ability to absorb contractual volumes, manage price risk and connect imported gas to demand centres through the domestic gas system.
The company’s description of India as a market that is still evolving suggests that its commercial model may need to adapt to local purchasing behaviour. Shaheen’s reference to headline prices points to the importance of the visible cost of imported gas in negotiations. Even where buyers value security of supply, the initial price of a contract can determine whether the gas is commercially usable across different customer segments.
This is particularly relevant for a fuel whose economics are shaped by several linked components: production, liquefaction, shipping, regasification and inland delivery. The supplied report does not provide a proposed Indian contract price or identify how Chevron would structure an agreement. It therefore cannot establish whether the company’s portfolio would be more competitive than alternative sources.
What it does establish is that Chevron sees a long-term opening. Shaheen said there would be “great opportunities over time”, while also making clear that immediate agreement was not guaranteed. The distinction separates a strategic market assessment from a confirmed investment or supply commitment.
## The changing logic of LNG contracts
Chevron’s comments also point to a broader change in the way LNG buyers are approaching supply. Shaheen said state-backed importers were increasingly willing to sign contracts with portfolio suppliers rather than relying only on government-to-government arrangements.
Portfolio suppliers can combine gas from multiple projects and regions, potentially offering buyers more flexibility in sourcing. That model is consistent with Chevron’s stated expansion strategy. Instead of depending on one field or one export country, the company would assemble volumes from a range of assets and contracted supplies.
For buyers, the attraction is the possibility of accessing a broader supply base. For suppliers, portfolio contracting can create a wider customer network and reduce dependence on a single destination. But the structure does not eliminate exposure to price or geopolitical risk. It changes how that risk is distributed across projects, contracts and markets.
India’s position in this changing system will depend on how its buyers weigh flexibility against certainty. The source material does not specify the contracting preferences of individual Indian companies, nor does it identify any ongoing negotiations with Chevron. The available evidence supports only the conclusion that the company is seeking an opportunity and that pricing is likely to be central to any discussion.
## Chevron’s competing capital priorities
The India opportunity is also competing with other projects in Chevron’s global queue. The company is considering further investments in Argentina, the East Mediterranean, Australia and Africa, while Chevron and its partners expect to invest more than $7 billion in Venezuela to more than double oil output by 2031.
Shaheen said all opportunities would be analysed and ranked in the project queue. He also indicated that capital requirements in Venezuela would be significant. That means any future LNG expansion, including a potential India arrangement, would have to compete internally for investment, management attention and available supply.
Chevron already has significant operations in Australia. It operates the Gorgon LNG project, described in the report as the country’s largest LNG project, and the Wheatstone project. A large portion of its Australian supply goes to Japan. Shaheen called Japan Chevron’s home base and said the company also had structural opportunities in Singapore, while China and South Korea remained attractive markets.
The company signed an agreement in Singapore in 2024 to supply Sembcorp Industries with up to 0.6 million tonnes per annum of LNG from 2028. That agreement provides a concrete example of the type of long-term commercial arrangement Chevron is pursuing in Asia. By contrast, its India comments remain exploratory and contain no equivalent volume or start date.
## The infrastructure question behind the deal
An India LNG agreement would ultimately be tested not only by the contract but also by the infrastructure and market system needed to use the gas. Imported LNG must move through a chain that includes shipping, receiving and regasification facilities, and onward distribution to customers. The supplied report does not identify the Indian terminal or network that could support a Chevron deal, so the infrastructure implications of a future agreement cannot yet be assigned to a particular city, state or project.
Still, the company’s comments illustrate how global energy-security decisions reach the urban economy. LNG is not simply an internationally traded commodity. Its usefulness depends on whether imported gas can be delivered at a price and through infrastructure that allows downstream consumers to use it. The commercial question therefore extends beyond Chevron and a potential Indian buyer to the institutions and networks that determine where gas can flow and who can afford it.
The report also shows why supply diversification does not automatically mean lower costs. Chevron is expanding across several regions because recent disruptions have increased the value of secure and varied supply. Buyers, however, must decide how much they are willing to pay for that security. India’s “headline-price driven” market may therefore reward suppliers that can combine reliability with competitive pricing, rather than reliability alone.
Chevron’s interest in India confirms that the country remains part of the global LNG opportunity, but it does not yet signal a completed transaction or a new import project. The evidence currently points to a company expanding its supply options, ranking competing investments and searching for commercially viable buyers. The next meaningful developments would be the identification of an Indian counterparty, the announcement of contract volumes and pricing terms, or confirmation of a delivery and infrastructure plan. Until then, the India opportunity remains a strategic possibility rather than a concluded deal.
