


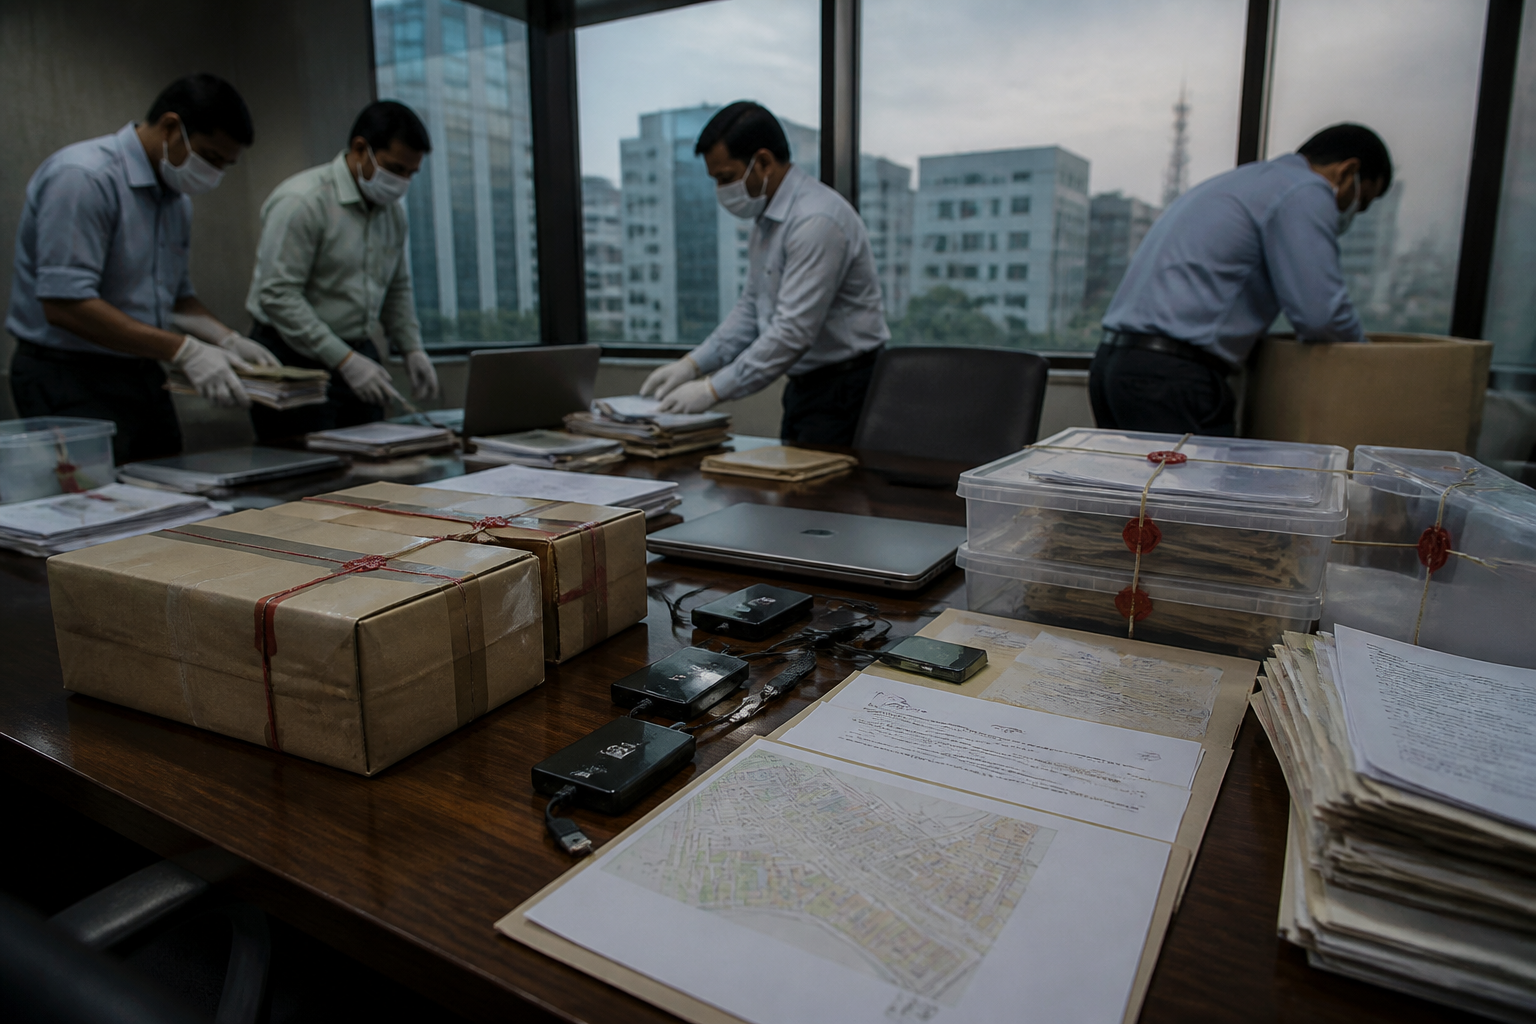
The Enforcement Directorate’s seizure of around Rs 82 lakh in cash, two luxury vehicles and electronic devices in Chennai and Tirupur has brought a long-running Indian Overseas Bank loan-fraud case back into focus. The agency’s action is not only about the assets recovered during searches; it also points to how alleged weaknesses in financial reporting, loan monitoring, related-party transactions and recovery processes can allow stressed corporate credit to move through wider urban business networks.
The searches were conducted on September 18 by the ED’s Chennai Zonal Office-II under the Prevention of Money Laundering Act, 2002. Six residential and office premises in Chennai and Tirupur were searched in connection with a suspected Rs 116.79-crore fraud involving PGC Corporation Ltd and its directors, D Prem, Aadith D Vikram and K Kaleeswaran. The case originates from a Central Bureau of Investigation-registered bank-fraud matter concerning Indian Overseas Bank.
According to the ED, PGC Corporation obtained loans from IOB and the account was classified as a non-performing asset in 2013 before being declared fraudulent in 2020. The agency has alleged that falsified and manipulated financial statements for 2011-12 were submitted to obtain enhanced credit facilities. These are allegations made in the course of the investigation and have not been established as final findings by a court.
The chronology is important because it shows the time gap between the original lending, the account becoming a non-performing asset and the later declaration of fraud. A non-performing asset classification indicates that a loan has stopped generating expected repayments under banking rules. A fraud declaration, however, involves an additional determination by the lender that the account contains fraudulent conduct. The information supplied in the case does not establish the precise internal decisions taken by the bank at each stage or explain when every alleged diversion was detected.
The ED has alleged that loan funds were diverted to personal accounts and foreign entities and subjected to round tripping. It further alleged that Prem and Aadith D Vikram created a network of domestic and foreign companies through which the money was moved as investments. Substantial amounts remitted abroad were allegedly brought back and used for local business expenses, according to the agency.
This alleged structure places corporate ownership and control at the centre of the investigation. The agency said that properties and assets were held in the names of the accused persons’ spouses and relatives. It also alleged that new businesses were established in the names of spouses and employees while the accused continued to manage and control their affairs. Such allegations make the distinction between formal ownership and effective control significant for investigators attempting to trace the movement of borrowed funds.
The case also involves an alleged disposal of inventory after the bank began recovery proceedings. The ED said inventory valued at more than Rs 235 crore belonging to PGC Corporation was sold to related entities without actual receipt of sale proceeds. The related entities were subsequently permitted to close without lenders’ approval, the agency alleged. The supplied material does not provide the inventory’s composition, its location, the terms of the alleged transactions or the identities of the entities involved.
For banks, the central institutional question is not limited to whether a borrower submits accurate statements at the time of seeking credit. It also concerns how lenders verify those statements, monitor the use of enhanced facilities, track inventory and identify transactions involving connected companies. The allegations in this case cover each of these stages: the submission of financial statements, the use of loan funds, transfers involving domestic and foreign entities, the sale of inventory and the treatment of related businesses during recovery proceedings.
The alleged movements of money across companies and jurisdictions also show why a corporate loan can become a matter of public financial governance. The original exposure was described as approximately Rs 116.79 crore, while the agency separately referred to inventory valued at more than Rs 235 crore. These figures relate to different parts of the allegation and should not be treated as a calculation of recoverable money or a final loss determination. The supplied report does not state how much of the loan has been recovered, what assets have been frozen previously or what amount the bank ultimately expects to realise.
The urban dimension is visible in the geography of the searches and the business relationships described by the agency. Chennai and Tirupur are connected to dense networks of corporate offices, manufacturing, trade, logistics, finance and property ownership. When bank credit is allegedly moved through companies, relatives and foreign entities, the consequences are not confined to a single office or borrower. They can extend into property records, business closures, lender recovery proceedings and the local commercial ecosystems in which companies operate. The supplied material, however, does not identify affected employees, suppliers, depositors or other creditors.
The investigation also illustrates the different roles of institutions. The CBI-registered case concerns the alleged cheating of IOB, while the ED is examining the suspected laundering of proceeds under the PMLA. The bank’s loan account history, the CBI case and the ED’s search action therefore form related but distinct parts of the process. A search and seizure does not itself determine guilt, establish the final quantum of loss or conclude the criminal proceedings. Those questions require further investigation and adjudication.
The seizure of cash, vehicles, laptops, pen drives, mobile phones, property documents and other material is significant because these items may help investigators reconstruct ownership, communication, transactions and asset flows. The report does not state what the seized devices contain, whether arrests have been made, whether any assets have been provisionally attached or whether the accused have responded to the allegations. Those omissions are important limitations when assessing the stage and likely direction of the case.
The account’s classification as a non-performing asset in 2013 and its declaration as fraudulent in 2020 also raise questions about the duration of the alleged exposure. The information supplied does not explain why the account remained unresolved over that period, what recovery measures were attempted or whether the alleged sale of inventory occurred before or after specific banking actions. Without those details, it would be premature to draw conclusions about institutional failure. The evidence does establish, however, that the investigation concerns events spread across several years rather than a single recent transaction.
For Chennai’s wider urban economy, the case is a reminder that financial infrastructure is part of the built environment’s operating system. Companies that borrow to hold inventory, expand offices or finance commercial activity depend on the credibility of banking records and enforcement mechanisms. When alleged diversion or concealment reaches property, company ownership and business closures, financial misconduct can intersect with the systems that organise urban land, employment and commerce.
The next stage will depend on what the ED establishes from the seized material and how the CBI-linked bank-fraud case proceeds. The available report confirms the searches, the assets seized and the allegations made by the agency. It does not establish final liability, the amount recovered or the outcome of the proceedings. Those facts remain to be determined through the investigation and the legal process.
