


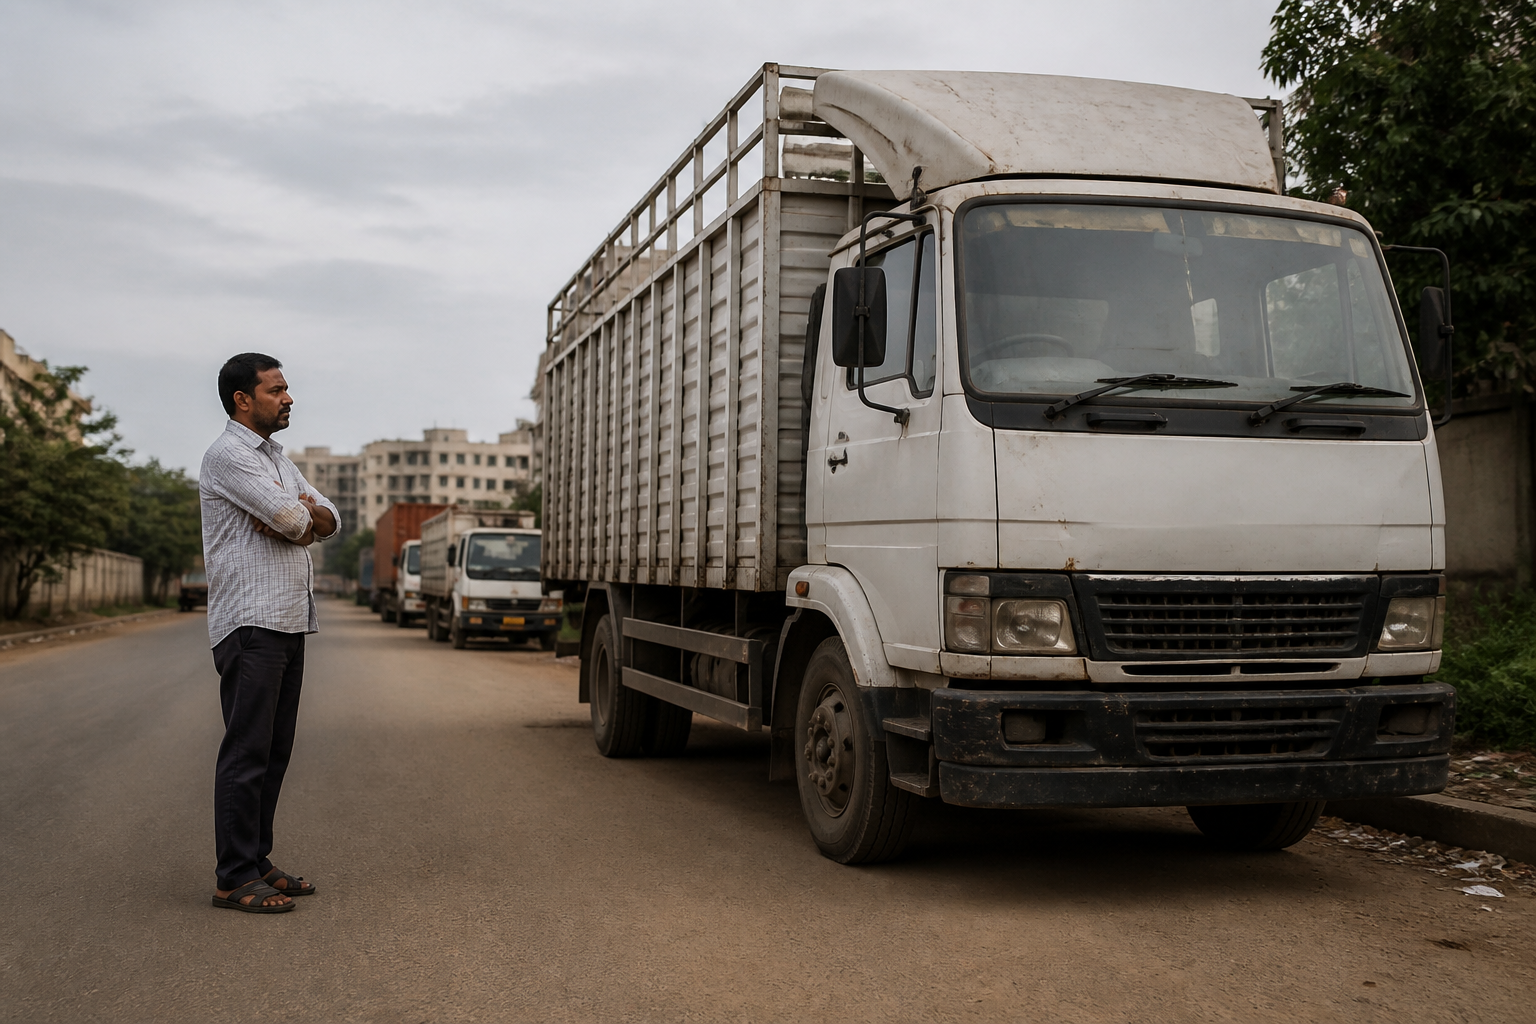
The Supreme Court’s ruling on vehicle-loan recovery has drawn a clear line between a finance company’s contractual right to repossess a vehicle and the use of force, threats or covert action to take it. The distinction matters far beyond one Tata SFC 407 truck: commercial vehicles are income-generating assets, and their sudden seizure can affect both a borrower’s livelihood and the functioning of local transport networks.
The case involved Hari Datta Sharma and Cholamandalam Investment and Finance Company. Sharma had taken a commercial vehicle loan for the truck and later alleged that four unidentified men arrived at about 1 am on 9 April 2023, broke the steering lock and drove the vehicle away. He also alleged that he had not received the required notice before the seizure. The report said he filed a lost-article report and an e-FIR on the same day.
A bench of Justices P S Narasimha and Alok Aradhe directed Cholamandalam Finance to return Rs 4.5 lakh with six per cent annual interest, pay Rs 10 lakh as compensation and provide Rs 50,000 towards litigation costs. The vehicle had subsequently been sold by the company for Rs 4.5 lakh on 31 August 2023, while the company continued to claim that Rs 5.71 lakh remained outstanding.
The judgment, as described in the supplied report, does not eliminate the possibility of repossession after a loan default. Instead, it examines how that power may be exercised. The court recognised that a loan agreement can contain a self-help repossession provision, allowing a lender in some circumstances to take possession without first pursuing a lengthy court process. But that contractual provision remains subject to law and fair procedure.
That distinction is central to vehicle-loan recovery. A lender’s right to recover its dues does not automatically authorise a recovery agent to enter a borrower’s premises, seize an asset at night or use intimidation. In practical terms, repossession is not the same as forcible removal. The legality of the outstanding debt and the legality of the recovery method are separate questions.
The dispute also exposed the importance of the loan agreement itself. The report said Sharma’s agreement contained a seven-day notice condition. The Supreme Court examined whether the relevant provisions effectively gave the company broad permission to take possession and sell the vehicle without adequate notice or a meaningful opportunity for the borrower to respond. The court’s approach places the written contract within a larger legal framework rather than treating every contractual clause as automatically decisive.
This is particularly significant for commercial vehicle borrowers. A truck, taxi, goods carrier or other commercial vehicle is not merely a financed object. It is often the means through which a borrower earns income and services a loan. If it is removed without warning, the immediate consequence can include loss of daily earnings, disruption to supply movements and greater difficulty in clearing the remaining debt. The supplied case involved a truck financed through a commercial vehicle loan, making the livelihood dimension direct rather than incidental.
The ruling also brings attention to the role of recovery agents. The report cited Reserve Bank of India master circulars, guidelines and other directions concerning recovery conduct. These rules require banks and finance companies to pursue repayment through lawful and fair methods and prohibit conduct involving threats, intimidation, harassment or the use of muscle power. They also address contact at inappropriate times and the behaviour of recovery agents acting on behalf of lenders.
The court’s concern, according to the report, was not limited to the existence of RBI rules. It also questioned whether those rules are effectively followed. This is an institutional issue: regulations can define acceptable conduct, but the borrower experiences the system through the agent who arrives at the door, makes a call or takes possession of the vehicle. The distance between a formal circular and street-level enforcement becomes the real test of regulatory protection.
The case therefore illustrates a recurring governance problem in credit markets. The lender may have a legitimate financial claim, while the recovery process may still violate legal and procedural standards. Treating default as permission for unregulated enforcement weakens confidence in both formal lending and the institutions meant to supervise it. The Supreme Court’s directions place responsibility on finance companies to ensure that recovery practices remain within the boundaries set by contracts, law and RBI instructions.
The facts also show why notice is more than a procedural formality. A notice period can give a borrower an opportunity to verify the outstanding amount, seek a settlement, arrange payment, challenge an error or understand the consequences of non-payment. It can also create a record of the lender’s action. Where a vehicle is later sold, documentation around notice, possession, valuation and sale becomes important to determining whether the process was fair.
The reported sequence raises questions about each of these stages. Sharma alleged that the truck was taken without the required notice. The company later stated that the truck had been sold for Rs 4.5 lakh. The company also continued to claim Rs 5.71 lakh from the borrower. The Supreme Court’s compensation order indicates that the dispute was not treated as a routine recovery matter, even though the lender retained a recognised interest in recovering its dues.
For borrowers, the practical lesson is that loan default does not erase their obligations, but it also does not erase their rights. The report advises borrowers who are unable to pay an instalment to contact the lender in writing and preserve records relating to dues, notices and payment deadlines. If repossession is threatened or undertaken, the borrower should examine whether the notice and possession process follow the loan agreement and applicable rules. These steps do not prevent a lender from enforcing a valid claim, but they can help establish what happened and whether the prescribed procedure was followed.
For lenders, the judgment underlines the need for tighter control over outsourced recovery operations. Finance companies cannot treat the conduct of an agent as separate from their own responsibility when that agent acts to recover the company’s money. Internal instructions, agent appointment and monitoring, notice records and sale documentation all become part of the accountability chain. The reported direction to send a copy of the judgment to the RBI also signals that the issue has implications beyond the individual company involved.
The case sits at the intersection of finance, mobility and urban livelihoods. Commercial vehicles connect markets, construction sites, neighbourhood deliveries and public-facing services. When financing is used to acquire these vehicles, repayment enforcement becomes part of the wider infrastructure of urban economic activity. A recovery system that is unpredictable or coercive can impose costs not captured in the loan account: interrupted work, loss of income and disputes over the asset’s removal and sale.
At the same time, the ruling does not establish that every repossession is unlawful or that a borrower can retain a vehicle indefinitely after default. Its significance lies in the conditions attached to enforcement. A lender may have a right to take possession in accordance with the agreement and applicable law, but that right cannot be converted into a licence for force, secrecy or harassment.
The evidence supplied in the report establishes the compensation awarded, the facts of the dispute, the court’s treatment of self-help repossession and its emphasis on RBI recovery guidelines. It does not provide the full text of the judgment or a broader dataset on vehicle seizures. What can be established from the case is narrower but important: the recovery of a financial debt must remain procedurally lawful, and the method used to seize a vehicle can itself attract judicial scrutiny even where a loan default has occurred.
The next institutional question is how finance companies and recovery agents implement these requirements in routine cases. The Supreme Court’s direction to send the judgment to the RBI places the regulator’s existing recovery framework under renewed attention. For borrowers and lenders alike, the test will be whether notices, possession and vehicle sales are handled through documented legal processes rather than improvised enforcement at street level.
