


Madhya Pradesh has introduced new input tax credit (ITC) conditions for hotel services, outdoor catering, electric-vehicle transport and certain delivery services, according to a report by Dainik Bhaskar citing a Commercial Tax Department notification issued on November 18. The provisions are treated as effective from November 1, 2026.
Under the reported rules, businesses in the affected services may not claim the full GST paid to another service provider in certain transactions. The eligible credit will be subject to specified conditions and a ceiling of 2.5 per cent.
For hotels, the provision applies when one hotel takes rooms or related services from another hotel and makes them available to customers. If the service provider has paid GST at a rate above 2.5 per cent, the recipient business will reportedly not be able to claim the additional tax credit beyond the prescribed limit.
Outdoor catering services, including arrangements for weddings and other functions, are also covered. Where a caterer hires another catering company to provide food services, the input tax credit on that transaction will reportedly be limited to 2.5 per cent, subject to other conditions in the notification.
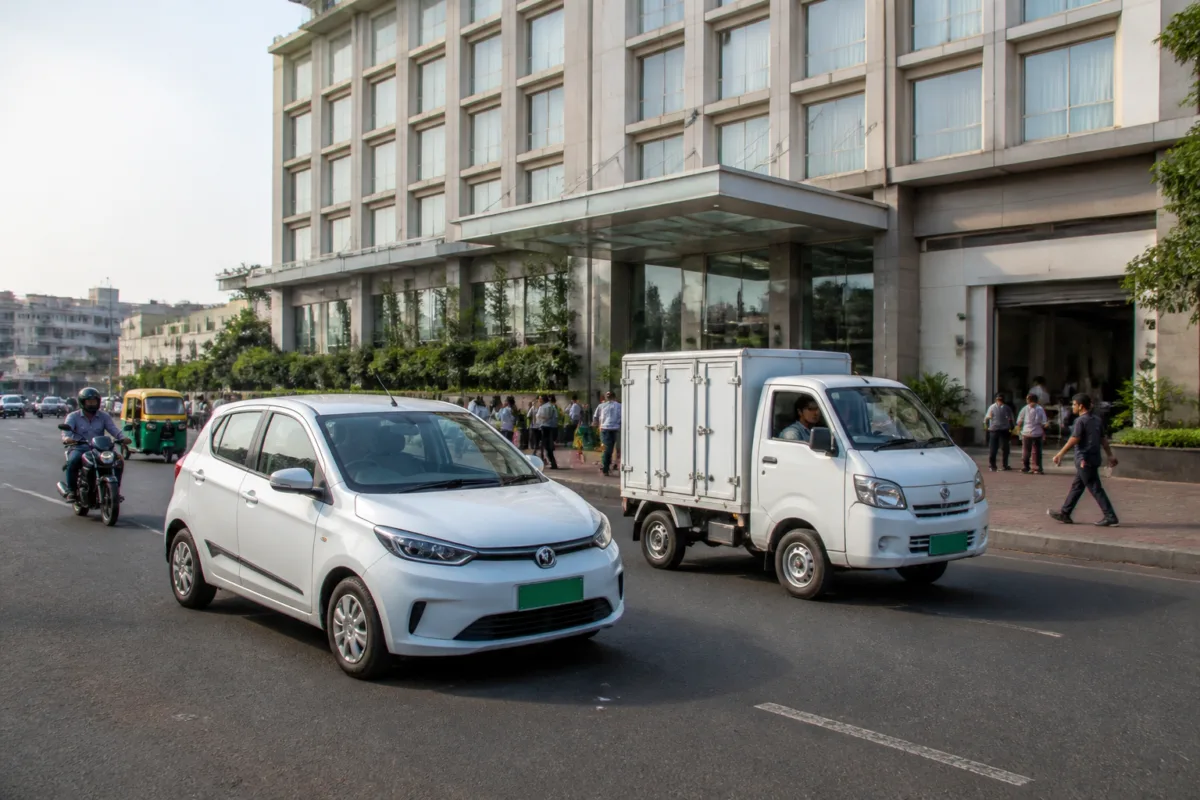
The changes also cover passenger and goods transport using electric vehicles. If a transport operator hires an electric vehicle from another service provider, the operator will be eligible for input tax credit only up to the reported limit. Dainik Bhaskar gave an example in which a service costing Rs 800 carried GST of Rs 72 at 9 per cent. Under the reported calculation, the recipient could claim a maximum credit of Rs 20, equivalent to 2.5 per cent of Rs 800, instead of the full Rs 72.
The notification also includes provisions for certain delivery services provided through e-commerce platforms. The report said credit for these services would be available only in accordance with the specified conditions.
Other areas mentioned in the notification include shared helicopter travel, storage and transportation of agricultural produce, and some institutional services. The report did not reproduce the full notification or detail every condition attached to these categories.
The changes are relevant to urban transport operators, hotels, caterers, delivery networks and businesses that depend on outsourced services. Their immediate effect will depend on how the notified conditions are applied to individual transactions and business arrangements.

