


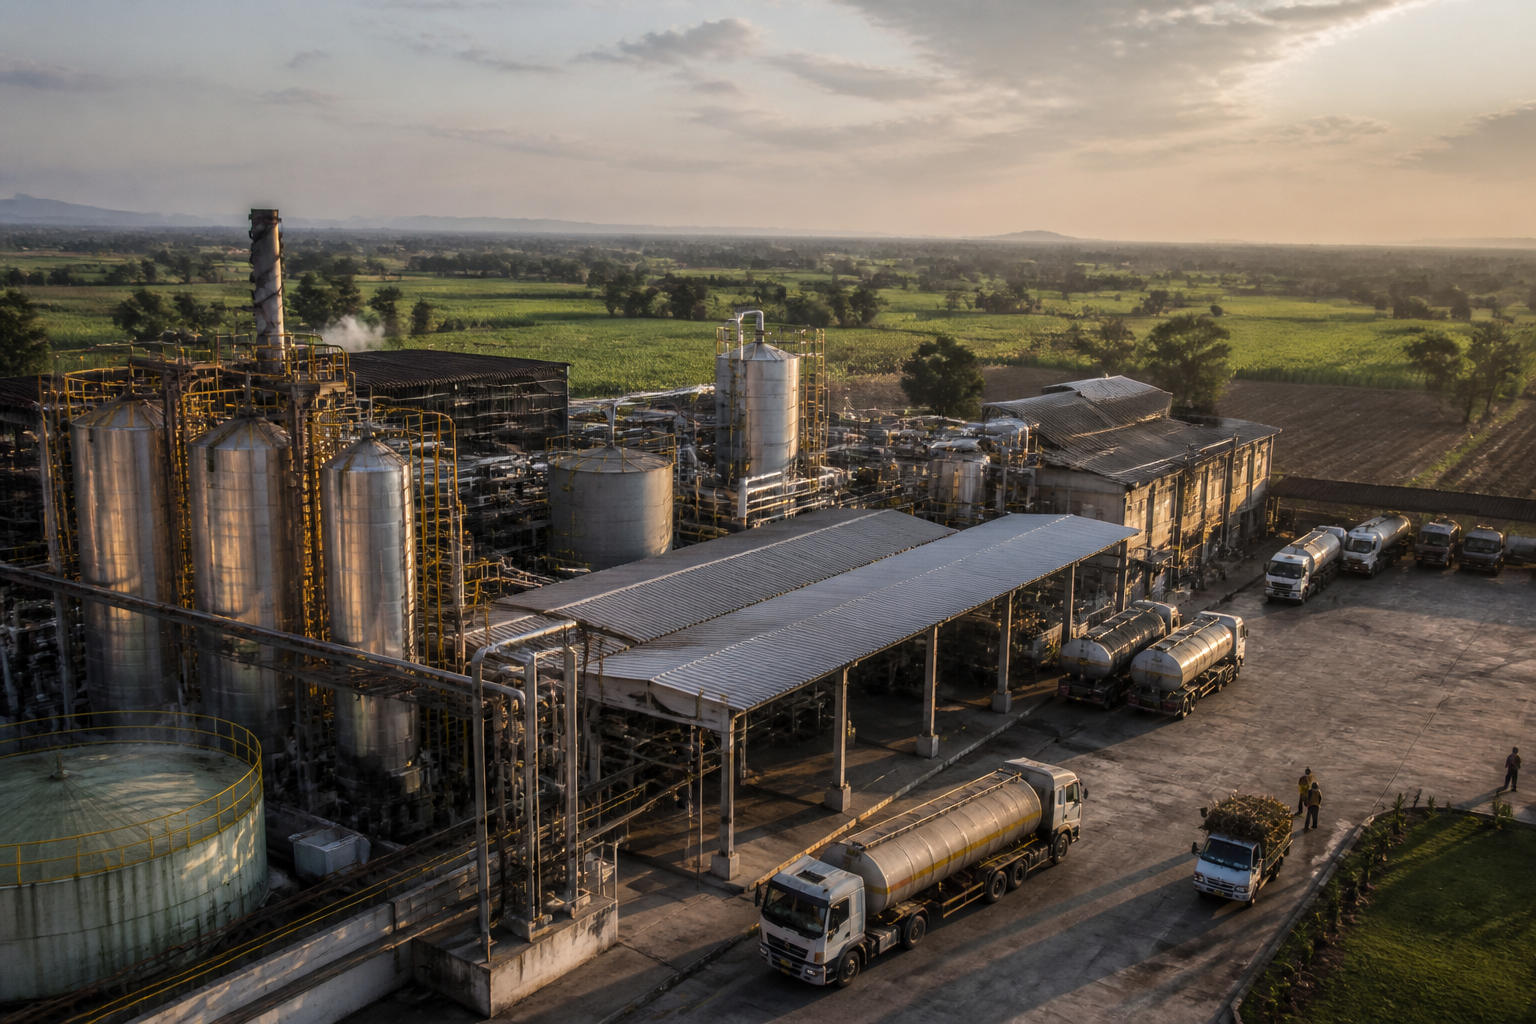
India’s ethanol surplus is no longer only an industrial problem. It is a test of how the country plans, finances and absorbs infrastructure built around a government-backed transition. Installed ethanol capacity has reached about 20 billion litres, but existing fuel and non-fuel demand accounts for only roughly 14 to 14.5 billion litres. The resulting gap of nearly seven billion litres has left distilleries searching for new buyers while operating substantially below capacity, according to figures and industry statements reported by The Economic Times.
The imbalance has emerged from the speed of capacity expansion. The government’s ethanol blending programme was designed to reduce dependence on imported crude oil and create a larger domestic market for agricultural feedstocks. Producers responded by adding distillation capacity, anticipating that higher blending mandates would steadily absorb more output. But the demand curve has not kept pace. The report says another four billion litres of capacity is expected to be added this year, even as the current E20 programme requires about 11 billion litres annually.
That creates a planning problem that extends beyond distilleries. Capacity is not the same as usable supply, and a blending target is not the same as guaranteed market demand. Ethanol must be purchased, transported, stored, blended and distributed through a fuel system that is also shaped by vehicle compatibility, oil marketing contracts and government decisions on future blending levels. When any part of that chain expands more slowly than production capacity, the investment case weakens.
The current numbers show how large the mismatch has become. Non-fuel sectors, including liquor, pharmaceuticals and chemicals, consume another 3 billion to 3.5 billion litres, according to the report. Together with the estimated E20 requirement, those markets account for most but not all of existing production potential. The remaining capacity has no clear outlet under current arrangements. Distilleries are reportedly operating at about 60% capacity, with utilisation expected to remain between 65% and 75% over the next three years.
The problem is unevenly distributed across the country. Maharashtra alone faced a projected surplus of 2.77 billion litres. This matters because ethanol production is tied to regional agricultural economies, particularly areas with sugar mills and grain-processing capacity. A market shortfall can therefore affect more than plant owners. It can influence procurement decisions, storage requirements, cash flows for distilleries and the wider industrial ecosystem built around feedstock processing.
The fuel-blending programme has also reached an important policy pause. The government has held back from mandating higher blends such as E25 or E30 after consumer opposition to E20. The roadmap remains capped at E20 until October 31, 2026, while the Centre has told the Supreme Court that the programme’s long-term impact will become clear only by 2027. That pause removes the immediate demand expansion on which some producers may have based their investment decisions.
This is the central institutional lesson in the surplus: supply-side incentives can move more quickly than the systems that create final demand. A distillery can be built within a relatively defined project cycle, but expanding the market requires coordination between the Union government, oil marketing companies, vehicle manufacturers, consumers, agricultural producers and regulators. It also requires certainty about fuel specifications, pricing, compatibility and the pace at which blending targets will change.
The delivery figures cited in the report illustrate the difference between policy ambition and actual offtake. By August, suppliers had delivered 8.95 billion litres to oil marketing companies against 10 billion litres contracted for the 2025-26 supply year, which runs from November to October. The shortfall does not by itself establish that the entire industry is unable to sell its output, but it does show that contracted demand and delivered volumes are not moving in lockstep.
One proposed response is to replace a single mandatory blending pathway with differentiated pricing for different blends. Ravindra Utgikar, chief sales officer at Wilo India, told The Economic Times that E10, E20 and E85 could be priced differently, allowing vehicle owners to choose fuel according to vehicle age, technology and compatibility. He pointed to the United States and Brazil as examples where different blends are available.
Such a model would change the administrative logic of blending. Instead of treating the vehicle fleet as a uniform demand base, it would recognise that cars and two-wheelers have different technical capabilities and operating costs. However, the supplied report does not establish whether India has the retail infrastructure, consumer information systems or pricing framework needed to implement such a model. It does show that the current approach has encountered a practical constraint: the market cannot be expanded indefinitely through mandates without accounting for vehicle compatibility and consumer acceptance.
Exports offer only limited relief under present rules. First-generation ethanol exports remain restricted, while India cleared only second-generation ethanol for export from September 2025. Small non-fuel volumes are being sent to Tanzania, Angola and Kenya, and the Grain Ethanol Manufacturers Association is in talks with Nepal, which plans a 10% blending mandate but lacks sufficient feedstock and distillery capacity. These channels may create individual opportunities, but they are not yet large enough to absorb India’s reported surplus.
The search for new markets is also pushing the industry towards fuels beyond petrol blending. The government and industry are exploring the possibility of blending ethanol derivatives with diesel. Ashish Gaikwad, managing director of Praj Industries, told The Economic Times that the company’s bio-isobutanol technology is ready for commercialisation and scale-up, with the first order expected in the current quarter of FY27. He said a 2% bio-isobutanol blending mandate in diesel could create a project opportunity worth more than Rs 3,000 crore.
That proposal is significant because diesel demand is larger than petrol demand, according to Gaikwad. But it remains an emerging avenue rather than an established market. The report does not provide a final government mandate, confirmed national volumes or a completed commercial rollout for bio-isobutanol. Its relevance lies in what it reveals about the direction of industry lobbying and technology development: producers are looking for new applications because the existing petrol-blending market cannot immediately absorb all available capacity.
The non-fuel market provides another important part of the picture. Not all ethanol becomes transport fuel. Undenatured ethanol used in liquor, pharmaceuticals and laboratories accounts for nearly 18.7% of demand, while the extra neutral alcohol market reached about 3.80 billion litres in 2025 and was growing at around 5% annually as consumers shifted from country liquor to Indian-made foreign liquor, according to the report.
This demand is substantial but not unlimited. It also operates under different regulatory and commercial conditions from fuel blending. Pharmaceutical and laboratory consumption depends on industrial requirements, while liquor demand is shaped by consumption patterns and state-level regulation. Treating these sectors as an automatic outlet for surplus fuel ethanol would therefore obscure the difference between technically possible use and commercially accessible demand.
The capacity gap also raises questions about how India measures the success of its ethanol policy. Higher blending can reduce petrol consumption and support energy-security objectives, but a plant’s economic viability depends on actual offtake, not only on national targets. If utilisation remains between 65% and 75% over the next three years, the country may have to manage a prolonged period in which capital is tied up in underused industrial assets while producers seek policy changes, exports or new technologies.
For cities and consumers, the issue is less visible than a new road or metro line, but its effects can still enter the urban system. Fuel availability, vehicle compatibility and retail pricing shape daily mobility costs. Ethanol production also connects urban demand to rural feedstock markets, industrial water and energy use, logistics networks and storage infrastructure. The policy therefore sits at the intersection of transport, agriculture, manufacturing and household expenditure.
The evidence currently confirms a capacity-demand mismatch, not the failure of the entire ethanol programme. India has a functioning blending market, substantial non-fuel demand and potential new applications under discussion. What remains uncertain is how quickly those markets can grow, whether higher blends will receive consumer and judicial acceptance, and whether exports or diesel-related applications can absorb the surplus at commercial scale.
The next phase of India’s ethanol policy will therefore be judged less by how much capacity is announced than by how reliably the market can use what has already been built. The E20 limit through October 31, 2026, the Supreme Court’s consideration of the programme’s longer-term impact, actual deliveries to oil marketing companies and the proposed commercialisation of bio-isobutanol will be the key markers of whether supply expansion can be brought back into line with demand.
