


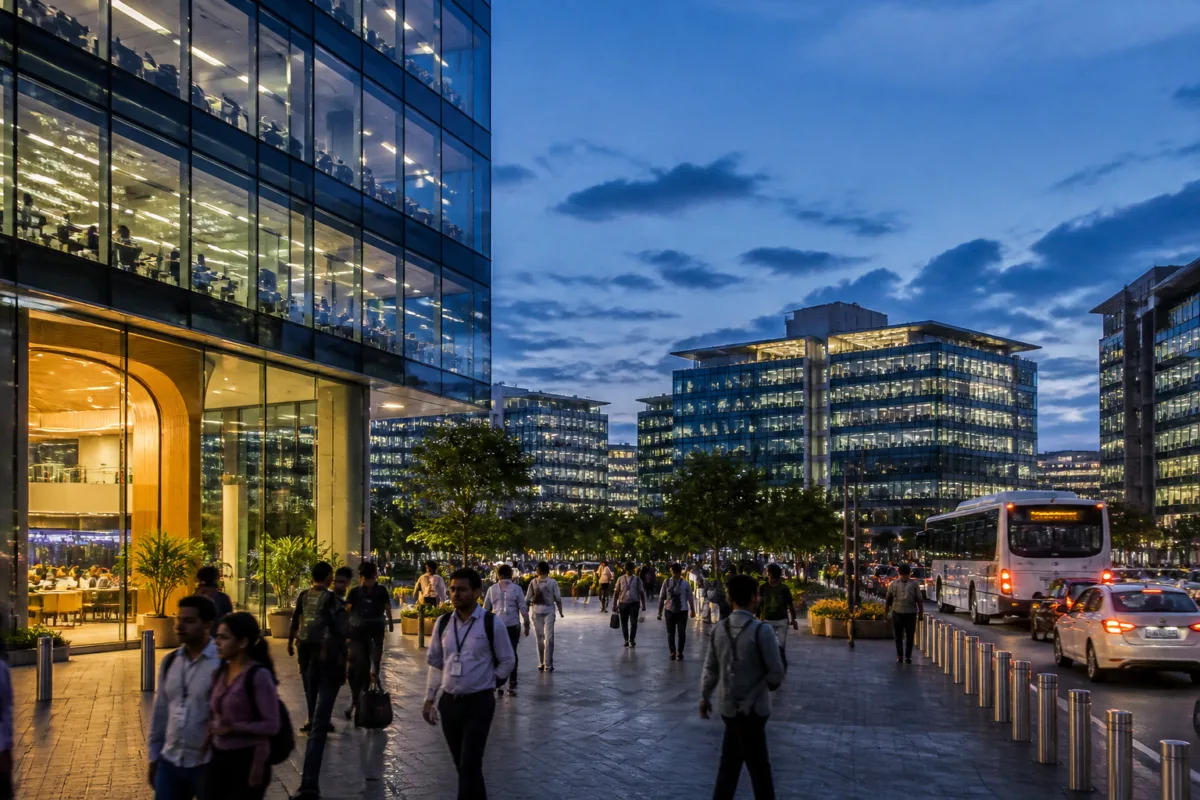
Global capability centres in India are becoming more than cost-saving offices for multinational companies, and that shift is reshaping the growth strategy of the country’s Big Four professional services firms. The segment generated more than $2 billion, or about Rs 19,000 crore, in combined revenue for these firms in FY26, according to figures and executive comments reported by the Economic Times.
The change matters because it places GCCs at the intersection of India’s technology economy, commercial real estate market, skilled employment base and corporate governance infrastructure. The centres are increasingly being positioned as strategic extensions of multinational companies, responsible not only for executing instructions from headquarters but also for product development, technology, experimentation, risk management and transformation.
That evolution is creating a larger role for firms such as Deloitte, EY, KPMG and PwC. Their proposition is no longer limited to audit, tax or traditional consulting. They are competing to help multinational companies establish, expand and transform GCCs, while also providing technology, talent, cybersecurity, infrastructure and operational expertise.
KPMG India’s global capability centre business contributed 30-35% of its overall advisory revenue in the last fiscal, according to Shalini Pillay, the firm’s India leader for global capability centres. Deloitte India’s GCC business is growing at 25% annually and accounts for 28% of its total revenue, the report said. EY India and Deloitte India each crossed Rs 5,000 crore in GCC revenue in FY26.
PwC India’s GCC practice accounts for 35% of its technology consulting business, its largest service line in India. Sanjeev Krishan, chairperson of PwC India, said the practice had more than 100 dedicated partners and 5,000 people and grew by about 35% year on year in FY26.
These figures show why GCCs have moved from being a specialist opportunity to a central business line. They also reveal a wider change in how multinational companies organise their operations in India. The country is no longer being used only for lower-cost managed services. It is increasingly being asked to host functions that influence products, platforms, business processes and long-term corporate decisions.
Global capability centres in India are becoming strategic twins
The first generation of GCC expansion was closely associated with cost-focused offshore work. The Economic Times report describes the period from 2017 to 2019 as one in which GCCs competed with third-party service providers for managed services and execution-heavy assignments. Their current role is different: they are becoming long-term partners to their parent companies.
Rajesh Ojha, partner and GCC market segment leader at PwC India, described the emerging model as a “strategic twin” that can own transformation and experimentation rather than merely execute work handed down by headquarters. This language captures the institutional change taking place inside multinational companies. Decision-making, product development and technology experimentation are no longer necessarily concentrated in the parent company’s home market.
The scale of the sector is significant. In FY26, more than 2,100 GCCs generated $98.4 billion in revenue in India and employed 2.36 million professionals, according to the figures cited in the report. Some projections mentioned in the report suggest that India could host as many as 5,000 GCCs by 2030, although that remains a projection rather than an established outcome.
For cities, the expansion represents more than a corporate-services trend. Large GCC operations require office districts, reliable digital connectivity, transport access, specialised talent, supporting vendors and security systems. Their growth therefore links corporate location decisions to the capacity of urban infrastructure and the availability of high-skill labour.
The report does not identify a single city as the centre of this expansion, but the operating requirements of GCCs point to the importance of established technology and business hubs. As companies move towards product development and platform building, the quality of the surrounding urban ecosystem becomes part of the business proposition.
The Big Four are selling lifecycle partnerships
The competition is also changing the commercial model of professional services firms. Rather than pursuing only individual consulting mandates, the Big Four are seeking longer-term relationships that cover the entire life of a GCC: setting it up, expanding its workforce and capabilities, and supporting transformation and innovation.
Deloitte is positioning itself as a lifecycle partner across the establishment, expansion and transformation of GCCs, according to Jaikumar Subramanian, GCC leader for diversified industries at Deloitte South Asia. The firm’s offering includes co-managed, completely managed, build-operate-transfer and hybrid structures.
These models matter because they determine who controls the operational architecture of a GCC and how much responsibility is transferred to an external partner. A company may ask a professional services firm to help build an operation and later retain it as a technology, talent, infrastructure or cybersecurity partner. The relationship can therefore extend well beyond a conventional three-year consulting contract.
The firms also argue that their advantage lies in combining technology delivery with sector knowledge, audit, tax, government regulations, risk and business processes. Prashant Choudhary, who leads financial services GCCs at Deloitte South Asia, said clients increasingly require domain expertise alongside technology capabilities.
That combination is especially important as GCCs move into regulated or operationally complex areas. A technology solution for a bank, insurer, manufacturer or healthcare company cannot be separated entirely from the rules, risks and processes governing that sector. The Big Four are using their existing institutional knowledge to compete for this more integrated work.
The economics of the model are also changing. Choudhary said some deals under consideration involved taking over large operations and delivering 35-40% efficiency. The claim is attributed to Deloitte and is part of the firms’ case for a transformation-led model rather than a headcount-led outsourcing model.
Artificial intelligence has opened a new competitive front
Artificial intelligence is intensifying the competition. The report indicates that GCCs are being asked to move beyond individual AI experiments and help companies prepare data, redesign processes and establish governance for wider deployment.
This expands the role of GCCs from technology users to institutional builders. Successful AI deployment requires more than access to a tool. It involves data systems, operating processes, oversight arrangements, cybersecurity and staff with sufficient domain knowledge. That creates an opportunity for firms that can combine technology implementation with risk and governance capabilities.
It also brings the Big Four into direct competition with technology services companies and specialist operators. PwC’s Ojha said knowledge alone was no longer sufficient and that the advantage would depend on how AI was applied to create outcomes. The statement reflects the shift from advisory expertise as a standalone product to implementation capacity as a core differentiator.
The next phase of GCC development is similarly connected to products and platforms. Subramanian said companies were seeking partners to develop technology products and platforms, requiring foundational capabilities in technology, talent, infrastructure and cybersecurity. In this model, a GCC is not simply a support centre; it becomes part of the parent company’s product and operating system.
For India’s technology cities, that could increase demand for specialised workers and higher-value office environments. However, the source material does not establish how this demand will be distributed geographically or whether the country’s urban infrastructure is keeping pace. Those questions remain important as the number of centres and the complexity of their work increase.
Competition is spreading beyond traditional consultants
The Big Four are not competing only against one another. Specialist GCC operators, talent providers and real estate companies are entering the market, increasing the number of participants to roughly 150-160, according to KPMG’s Pillay.
This wider field changes the basis of competition. A professional services firm may have an advantage in regulatory understanding and transformation, while a specialist operator may compete through talent acquisition, speed or operating expertise. Real estate players can influence location, office design and the physical infrastructure needed to establish large corporate centres.
The location of decision-making creates another layer of complexity. GCC mandates often originate at a multinational’s headquarters even when most of the work is carried out in India. Winning the business therefore requires coordination between the Indian practice and the firm serving the client in its home market.
This cross-border structure means that India’s position in the GCC economy depends on more than domestic cost advantages. It also depends on the ability of Indian operations to demonstrate specialised expertise, manage global risk and deliver work that affects the parent company’s products and strategy.
The reported premium billing rates underline both the opportunity and the pressure. GCC projects can attract rates 30-40% higher than traditional domestic engagements, Pillay said, but pricing pressure is rising as larger firms expand their presence. Growth will therefore depend on specialised expertise, innovation and measurable value rather than pricing alone.
The larger urban question is whether India’s cities can support this transition from back-office expansion to strategic corporate activity. GCC growth creates demand for skilled employment, high-quality offices, digital systems and dependable infrastructure. It may also deepen the concentration of high-value work in cities that already possess strong technology and business ecosystems.
The evidence currently establishes the scale of the market, the shift in the work being performed and the intensity of competition among service providers. It does not establish whether the projected expansion to 5,000 GCCs by 2030 will occur, how evenly the benefits will be distributed across cities or how much of the work will be altered by AI. Those developments will determine whether India’s GCC sector remains primarily an employment and outsourcing story or becomes a deeper platform for product creation, governance and urban economic growth.

