


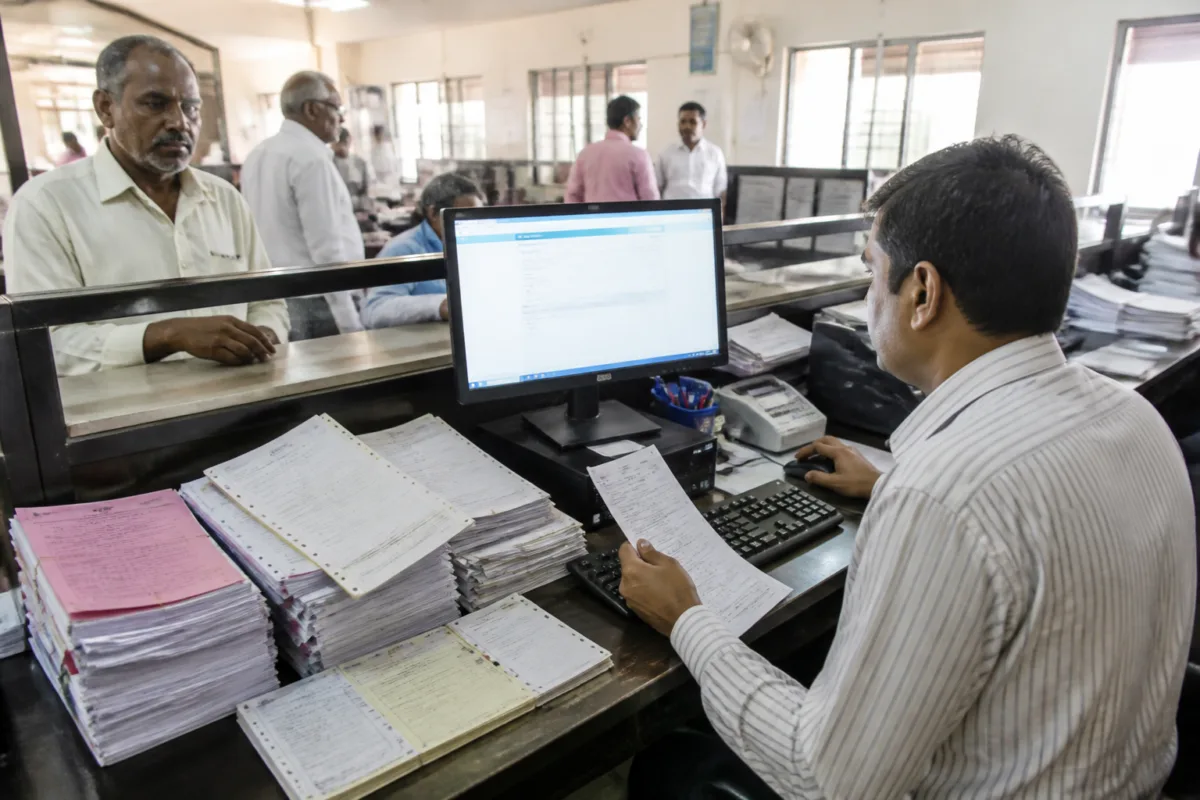
A report alleging repeated breaches of financial procedures in the Ahmedabad Municipal Corporation (AMC) has put the spotlight on a basic governance question: whether the civic body’s systems are strong enough to track public money from collection to deposit. The issue has resurfaced alongside an instruction from the municipal Finance Department to move receipts and revenue records online, signalling an administrative attempt to reduce the risks associated with manual cash handling.
The report by Nav Gujarat Samay – Ahmedabad says financial rules in the civic body have allegedly been overlooked for some time. It refers to instances of suspected embezzlement and claims that some cases may not have received public attention. These claims are attributed to the report and to unnamed municipal sources; the supplied material does not provide independent audit findings, police records or official responses confirming each alleged incident.
The reported concern is not limited to one department. According to the report, large amounts are transacted every day in Ahmedabad’s municipal system, including through city civic centres and other departments. Such points of collection are where residents pay for municipal services, permissions or other civic transactions. When receipts are issued manually or when staff without permanent municipal status handle financial transactions, the chain of accountability becomes more difficult to audit, the report indicates.
The issue had previously been raised by the person who is now the Ellisbridge legislator, when he was serving as Ahmedabad’s mayor and a corporator. The report says he had told the municipal board that contract workers should not be appointed to positions involving financial transactions and that such responsibilities should be assigned only to permanent employees. Despite that earlier objection, the report says contract workers continue to handle financial transactions at several locations.
That alleged gap between a stated rule and actual practice is central to the story. A financial control is useful only when responsibilities are clearly assigned, access is limited and transactions leave a verifiable record. If a civic body continues to rely on arrangements that its own political or administrative leadership has previously questioned, the formal rule may exist without producing effective control on the ground.
The report cites two examples of alleged embezzlement. It says that, during the earlier operation of the new West Zone, two or more employees allegedly acted together to misappropriate lakhs of rupees. It also refers to a recent case involving an assistant-level employee from the Estate Department posted with the Fire Brigade, who allegedly misappropriated lakhs of rupees. The supplied report does not state the exact amounts, the dates of the alleged incidents, whether criminal complaints were filed or whether departmental inquiries have been completed.
Those limitations matter because an allegation of financial misconduct is not the same as an established finding. The report’s account points to possible weaknesses in AMC’s financial administration, but it does not establish the final legal or disciplinary status of the cases it mentions. A complete public record would need to identify the transactions involved, the responsible supervisory officers, the recovery or loss amount, and the outcome of any investigation.
The report also raises a separate control issue involving employees and officers approaching retirement. It says AMC rules require financial powers to be withdrawn three months before an employee or officer retires. However, it alleges that in some cases officials continued signing files until retirement. If accurate, this would indicate a failure in a time-bound administrative safeguard rather than merely an isolated lapse by an individual employee.
The purpose of such a rule is to create a clear boundary for financial authority. Removing signing powers before retirement can allow the administration to review pending files, reassign responsibility and ensure that transactions authorised near the end of an officer’s service are properly accounted for. The report does not provide the number of cases in which the rule was allegedly breached, but the question it raises is straightforward: whether the rule is systematically monitored or left to individual departments to implement.
The strongest institutional response described in the report comes from the municipal Finance Department. It has instructed all departments to register every form of revenue online and to issue receipts to applicants through online channels. Departments that still issue handwritten receipts have reportedly been given 15 days to shift all revenue collection to e-challan and online acceptance. Where a manual receipt is issued, responsibility will rest with the concerned department, according to the report.
Digitising receipts can create a more traceable record of collections. An online receipt can link the payer, department, transaction amount and date in a way that is harder to alter or remove than a handwritten document. It can also reduce the number of steps through which cash passes before it is entered into municipal accounts. However, the supplied material does not explain the technology being used, the departments covered, the audit process or how exceptions will be handled.
The 15-day deadline is therefore an important administrative milestone, but not proof that the control problem has been solved. The directive transfers responsibility to departments still using manual receipts and creates a formal deadline for change. Its effectiveness will depend on whether AMC can identify every collection point, disable unauthorised manual processes, reconcile existing receipt books and review transactions after the digital system is introduced.
The transition also has a citizen-facing dimension. City civic centres and other municipal counters deal directly with residents, many of whom require proof that a fee or charge has been paid. An online receipt system could make that proof easier to retain and verify. At the same time, the report does not discuss access for residents who may be unable to use digital channels, nor does it say whether assisted payment and receipt facilities will remain available.
For municipal administration, the broader challenge is to connect personnel rules, financial authority and transaction records. Restricting financial work to permanent staff, withdrawing powers before retirement and digitising receipts are separate measures, but they address the same problem: ensuring that each public transaction has an identifiable owner and an auditable trail. If one part of that chain fails, the presence of the other controls may not be sufficient.
The report’s allegations also highlight the difference between prevention and detection. A rule against assigning financial transactions to contract workers is preventive. A retirement-related withdrawal of powers is preventive. Online receipt registration is both preventive and documentary. But suspected embezzlement cases require detection through reconciliation, internal audit, supervisory review and, where necessary, investigation by competent authorities. The supplied material does not establish how frequently AMC performs these checks or whether findings are published.
The immediate evidence therefore supports two conclusions. First, AMC’s Finance Department has recognised manual revenue collection as a control risk and ordered a shift to online receipts within 15 days. Second, the report describes alleged failures in staffing, financial authority and oversight that suggest the problem may extend beyond the format of a receipt. What remains unclear is the scale of the alleged losses, the status of the cited cases and whether the directive will be followed across all municipal departments.
The next point to watch is implementation of the Finance Department’s deadline. The administrative record should show which departments completed the transition, whether manual receipt books were withdrawn, and how pending and past collections were reconciled. Those steps will determine whether AMC’s response becomes a durable financial-control reform or remains another instruction whose effectiveness depends on departmental compliance.

