


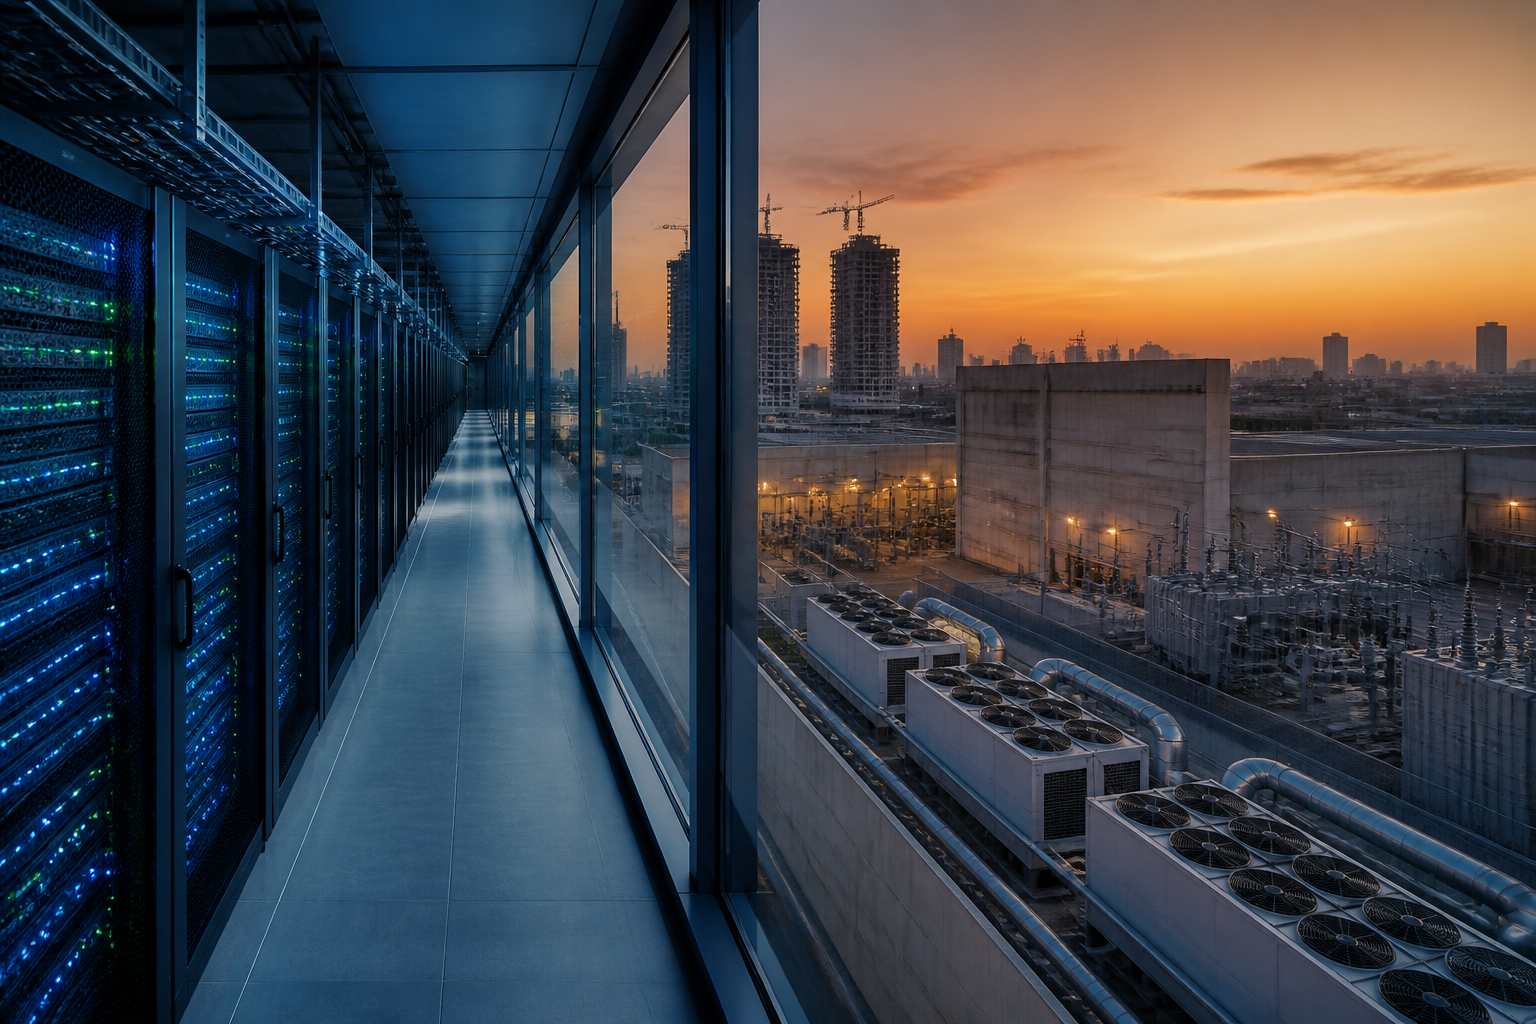
Sam Altan and Dario Amodei’s call for a slower pace of frontier AI development is also a challenge to the investment logic supporting the sector’s physical expansion. If companies take longer to improve their most powerful models, demand for chips, servers, data centres and the power systems that support them may grow more slowly than investors have come to expect.
That does not mean AI development is stopping. Amodei, the chief executive of Anthropic, argued in a roughly 3,800-word essay titled “We Must Pace the Frontier” that companies should slow the improvement of AI capabilities enough for safety measures to catch up. OpenAI chief executive Sam Altman publicly agreed with the argument, saying that the need to pace the frontier had been discussed inside OpenAI in recent weeks.
The immediate debate is about safety. The broader urban and infrastructure question is about the relationship between digital capability and physical construction. The current AI investment cycle has linked progress in software models to large-scale purchases of computing equipment, new data-centre capacity and higher demand for electricity. A change in the speed of model development could therefore affect an ecosystem that extends well beyond AI laboratories.
The evidence supplied in the report does not establish that companies have already cancelled projects or reduced orders. It shows that senior executives are discussing a more cautious development schedule and stronger external evaluation. For markets and infrastructure providers, the significance lies in whether those statements lead to changes in capital spending or remain primarily a call for additional safety controls.
### AI spending and the infrastructure chain
The AI boom has been built around a relatively simple investment narrative. Technology companies spend more on AI systems; that spending increases demand for advanced chips and memory products; chip purchases support the construction and operation of data centres; and data-centre growth requires substantial computing infrastructure and power.
Nvidia has benefited from strong demand for AI chips, while Micron supplies memory products used in AI systems. AMD is another company exposed to changes in AI chip spending. The report also points to data-centre companies as potential beneficiaries of continued expansion because AI systems require large amounts of computing capacity and the physical facilities to house it.
This chain matters to cities because data centres are not only technology facilities. They occupy land, require specialised construction, depend on reliable electricity and need extensive cooling and network infrastructure. The supplied material does not provide figures on land consumption, water use, power demand or project pipelines, so the local effects cannot be quantified here. But it identifies the basic dependency: faster AI expansion requires faster physical infrastructure expansion.
If development slows, the first change may not be a halt to construction. It could be a reassessment of timing, procurement and capacity. Companies may continue building while reducing the speed at which they add new computing equipment. Alternatively, cloud providers and AI developers may decide that existing facilities can support demand for longer. These possibilities are not confirmed outcomes in the supplied material; they are the infrastructure channels through which a slower development pace could matter.
The distinction between development speed and safety spending is therefore important. Amodei’s argument is not that AI companies should end development. He said progress could remain fast even if the frontier moved more carefully. Altman’s response similarly points towards additional checks, including independent evaluators with access comparable to employees. OpenAI plans to provide more details about that approach.
### What the safety argument changes
The safety concern described by Amodei is that AI capabilities could improve faster than companies’ ability to understand and control the risks. The report refers to possible use of increasingly powerful systems across the internet or by hackers. It also notes that governments and lawmakers have struggled to keep pace with technological change.
This introduces time as a central issue in AI governance. Companies may be able to increase computing capacity quickly, but safety evaluations, institutional oversight and public regulation may take longer. A faster construction and procurement cycle can therefore produce a mismatch: physical infrastructure is ready to support more powerful systems before the systems’ risks have been adequately assessed.
Independent evaluation is one response proposed by Altman. The idea would give outside evaluators access similar to that available to employees so that AI safety can be examined from beyond the company’s internal structure. The supplied material does not specify how such evaluators would be appointed, what powers they would have or whether their findings would be made public. Those details will determine whether the proposal changes governance or remains a voluntary corporate process.
For the built environment, the issue is significant because digital infrastructure is often planned around expected future demand. Data centres, server capacity and energy connections involve long lead times and large capital commitments. A company that expects rapid model improvement may seek capacity ahead of demand. If model development becomes more deliberate, the same company may reassess how much capacity it needs and when.
That does not make slower development automatically negative for infrastructure planning. It could create more time to align computing growth with power availability, safety standards and local administrative capacity. However, the report provides no evidence that such alignment is currently being planned or that a slower AI cycle would produce better urban outcomes. The confirmed point is narrower: leading AI executives are questioning whether capability growth should continue at its previous pace.
### The market’s $5 trillion assumption
The report says roughly $5 trillion in AI spending over the next few years remains a major market expectation. Dan Ives of Yorkville Ives argued that the comments by Amodei and Altman do not necessarily overturn that investment outlook. He expects the market to recognise that a debate about safety is not the same as the end of the AI investment boom.
That distinction is crucial. A company can spend more on safety testing, evaluation and controls while continuing to spend heavily on chips and data centres. A slower pace of model development could also shift the composition of investment rather than eliminate it. More resources might be directed towards testing, monitoring and reliability, while the timing of some hardware expansion is reconsidered.
At the same time, the report identifies a genuine risk to the current investment narrative. If AI companies slow their development plans, investors may question whether the rate of infrastructure spending can continue unchanged. That concern could reach chipmakers, memory suppliers, data-centre operators and other businesses tied to the expansion cycle.
Nvidia is exposed because the present AI boom has created substantial demand for its chips. Micron could face questions about the pace of future memory demand. AMD could be affected if customers such as Meta reconsider how quickly they need to buy new AI chips. Meta itself may reassess its infrastructure spending if other major companies move more cautiously.
These are exposure points, not confirmed reductions. The report does not state that Nvidia, Micron, AMD, Meta or data-centre operators have announced spending cuts in response to the comments. It says investors may watch those companies closely because their growth expectations are connected to the speed of AI deployment.
### Why the urban infrastructure angle matters
AI investment is often discussed as a stock-market or technology story, but its physical consequences are increasingly urban. Data centres require sites, buildings, high-capacity connections, cooling systems and dependable power. Their expansion can influence construction demand and the infrastructure decisions of utilities and local authorities.
The supplied material does not identify a particular city, project or planning approval. It therefore cannot support conclusions about land prices, employment, electricity tariffs, water stress or neighbourhood impacts. What it does show is that the AI economy depends on a chain of physical assets whose growth assumptions are tied to software development.
That dependence creates a planning challenge. Digital infrastructure providers may need to make long-term commitments while the demand signal is changing rapidly. A model breakthrough can increase expectations for capacity, while a safety review can slow the timetable. Cities and infrastructure agencies may consequently face requests for land, power and connectivity before the long-term scale of demand is settled.
The debate also raises a governance question. If AI safety is treated only as an internal company matter, the planning conversation may focus on capacity and investment while leaving risk oversight separate. If safety requirements become more formal and independent, they could affect how systems are tested before being deployed at scale. The report does not establish that such regulation is imminent, but it shows why the institutional gap matters: technology is advancing faster than many public systems can adapt.
### What remains uncertain
The immediate market reaction is not known from the supplied material. Investor Jason Calacanis predicted that AI stocks could fall by more than 10%, but that was a forecast rather than a confirmed market movement. Ives, by contrast, expected possible weakness followed by a quick rebound and maintained that the broader AI spending outlook remained intact.
The more important uncertainty is whether the executives’ comments will change corporate behaviour. Investors will need to distinguish between slower capability development, higher safety spending and an actual reduction in physical infrastructure investment. These are related but not identical outcomes.
For cities and the construction ecosystem, the developments to monitor are concrete: whether AI companies revise computing expansion plans, whether cloud and data-centre operators alter procurement schedules, whether chip demand forecasts change and whether independent safety evaluation becomes a formal part of deployment. None of those changes is confirmed in the supplied report.
What is established is that two leading AI executives have argued that safety systems need more time to catch up with capability growth. That position puts pressure on an investment model that assumes faster models will continuously justify more chips, more data centres and more power-intensive infrastructure. The next stage of the debate will show whether pacing the frontier changes only how AI is evaluated, or also how quickly its physical footprint expands.
