


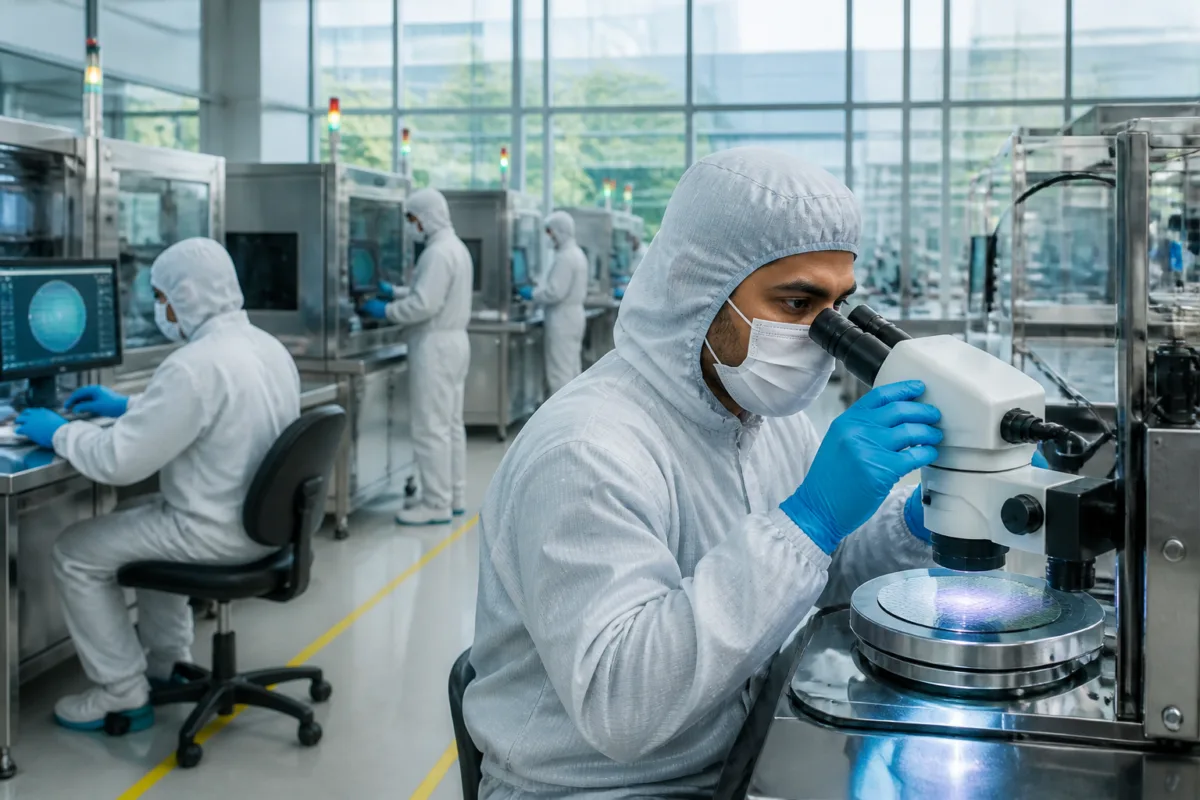
India’s semiconductor jobs boom is gathering pace, but the workforce numbers also expose the harder problem behind the manufacturing ambition: the country may be able to attract investment faster than it can produce experienced engineers for specialised factory and systems roles. Estimates cited by Boston Consulting Group and CIEL HR Services point to tens of thousands of new openings, rising salaries and a sharp expansion of demand beyond the chip-design work that has traditionally defined India’s semiconductor presence.
The scale of the expected expansion is significant. Industry estimates cited in the report suggest that more than one lakh jobs could be created over the next three years as India develops a semiconductor ecosystem of its own. A separate CIEL HR Services study estimates that companies could add about 67,500 jobs in the next 18 months. The two figures cover different periods and are based on separate assessments, but together they show how quickly hiring expectations are moving.
That expansion is also changing the type of work being sought. Semiconductor recruitment in India has historically been concentrated in design, verification, engineering, testing and product development. The emergence of domestic fabrication and packaging capacity is now creating demand for process engineering, equipment maintenance, yield management, reliability engineering and advanced packaging. These roles are closely tied to the operation of physical production facilities rather than only to design offices.
This distinction matters for cities and industrial regions. A design-led semiconductor workforce can be concentrated in engineering and technology offices, while fabrication, packaging and testing require a wider operating ecosystem. That ecosystem includes specialised industrial facilities, equipment maintenance, process control, logistics and technical training. The supplied report does not identify the locations of the new facilities or quantify their infrastructure needs, but its hiring data indicates that India’s semiconductor expansion is moving towards a more complex built and industrial environment.
BCG estimates that India’s semiconductor workforce, currently pegged at 25,000, could expand fourfold over the next three years. At the same time, the CIEL study places the broader number of semiconductor professionals at around 1.5 lakh across chip design, verification, engineering, testing and product development. These figures should not be treated as interchangeable. They appear to reflect different definitions of the semiconductor workforce, making the composition of the talent base as important as its headline size.
The difference between the estimates also points to a measurement challenge. A workforce count restricted to a narrower set of semiconductor roles will produce a different baseline from one covering the wider chain of design, testing and product development. Without a common definition, it becomes difficult to assess whether training pipelines are expanding fast enough, whether companies are competing for the same people, or whether the growth is creating genuinely new capabilities rather than shifting employees between firms.
The immediate shortage is concentrated at the senior end. Ankush Wadhera, partner and managing director at BCG, said the supply of fit-for-role talent was not keeping pace with demand and that many companies were looking outside India for senior professionals. He said entry-level and mid-level workers could be trained more readily, while senior talent remained in acute shortage.
The report says the United States and Southeast Asia have become important destinations for companies seeking experienced professionals, with a significant share of the global talent pool comprising members of the Indian diaspora. This creates a structural constraint for India’s manufacturing plans. New facilities require people who understand not only semiconductor theory but also the practical realities of running equipment, controlling yields, managing reliability and bringing products to production.
The salary premium reflects that scarcity. Professionals with specialised expertise in process engineering, chip fabrication, chip design, systems engineering and product architecture can earn four to six times the salaries of IT services professionals with similar experience, particularly at mid- and senior levels. Such pay differences can draw experienced workers into the sector, but they also raise the cost of building a domestic ecosystem and intensify competition between semiconductor companies, technology firms and other employers.
The CIEL study provides another indication of the imbalance. It found that for every 100 engineers with expertise in microarchitecture, the industry had 135 vacancies to fill. The ratio suggests that hiring pressure is not limited to one company or one isolated project. It reflects a wider gap between the number of workers with sought-after expertise and the number of roles companies are seeking to fill.
The demand profile is technically specific. Employers are seeking professionals skilled in physical design and timing closure, digital design and register-transfer-level coding, design verification, microarchitecture, emulation, formal verification, embedded systems and silicon bring-up. Programming skills in Python, C++, Verilog and System Verilog are also in demand. These requirements create a more demanding training problem than simply increasing the number of engineering graduates.
The CIEL assessment, based on semiconductor recruitment trends during the 12 months leading up to November 2026, examined approximately 45,000 job openings across more than 150 semiconductor companies. It also found that about 43% of the workforce had more than 10 years of experience, while nearly three-fourths had more than five years of experience. Those figures underline why companies cannot rely only on entry-level recruitment: a large share of the work requires accumulated technical and operational experience.
The list of companies with current openings further illustrates the breadth of the market. Qualcomm has the highest number of openings in the study, followed by AMD, Nvidia, Synopsys, Applied Materials, Infineon, Cadence and Micron. These companies span chip design, electronic design automation, equipment and semiconductor manufacturing, meaning that the competition for talent is spread across different parts of the value chain.
Aditya Narayan Mishra, CEO of CIEL HR Services, said domestic fabrication and packaging units were creating demand for roles that had previously represented a negligible share of hiring. These include process engineering, equipment maintenance, yield management, reliability and advanced packaging. The shift is important because it changes the relationship between India’s semiconductor industry and its urban economy.
India’s earlier advantage in the sector was strongly associated with engineering talent and design services. The next phase requires a broader industrial workforce. That means the relevant labour market is no longer limited to software and engineering offices. It must also include workers able to operate and maintain high-value equipment, manage production quality and support the physical movement of sensitive products and components.
The supplied evidence does not establish how many training institutions, industrial clusters or public programmes are currently aligned with this demand. It also does not provide a city-by-city breakdown of vacancies, salaries or new facilities. Those gaps matter because workforce expansion is ultimately experienced locally. The success of a semiconductor ecosystem will depend not only on the number of national openings, but on whether specific locations can support specialised workers, industrial operations and the services required around them.
This is where the employment story becomes an urban systems question. A new manufacturing ecosystem can generate demand for housing, transport, utilities, logistics and technical education near production locations. However, the report does not quantify such requirements or identify which cities will absorb the expected growth. The evidence supports the conclusion that the workforce is broadening; it does not yet support claims about the scale or distribution of associated urban development.
The institutional challenge is therefore two-sided. Companies need to recruit and train workers, while the wider ecosystem needs a reliable pipeline of technical education and industrial support. Firms are already looking beyond semiconductor competitors, including to academic institutions and IT services companies, to meet hiring requirements. That approach may widen the pool, but it also transfers part of the adjustment burden to universities, training providers and adjacent industries.
The data also shows why a national jobs figure can conceal operational risks. More than one lakh prospective jobs sounds like a broad employment opportunity, but the most serious shortage is among experienced professionals. A fourfold increase in the BCG workforce estimate would not automatically resolve the shortage if growth is concentrated in entry-level positions while factories and advanced design operations continue to require senior personnel.
The central evidence, then, is not simply that semiconductor hiring is rising. It is that India is attempting to expand across a sector whose skills are unevenly distributed. The country has a substantial base of professionals across design, verification, engineering, testing and product development, but companies report a sharper shortage in specialised and senior roles. The move into fabrication, packaging and related operations is increasing the range of capabilities required.
India’s semiconductor opportunity will therefore be tested by conversion: whether projected vacancies become trained workers, whether experienced talent is retained or attracted back, and whether the locations hosting the industry can support its industrial and workforce needs. The current estimates confirm strong demand and a widening employment pipeline. They do not yet establish how quickly training capacity, senior expertise and local urban infrastructure can catch up.
The next developments to monitor are the actual distribution of the projected 67,500 openings, the extent to which fabrication and packaging roles grow relative to design jobs, and whether the reported shortage of senior talent narrows. A clearer, common definition of the semiconductor workforce will also be necessary to reconcile the differing estimates and measure whether India’s manufacturing ambition is producing a durable ecosystem rather than only a surge in vacancies.

