


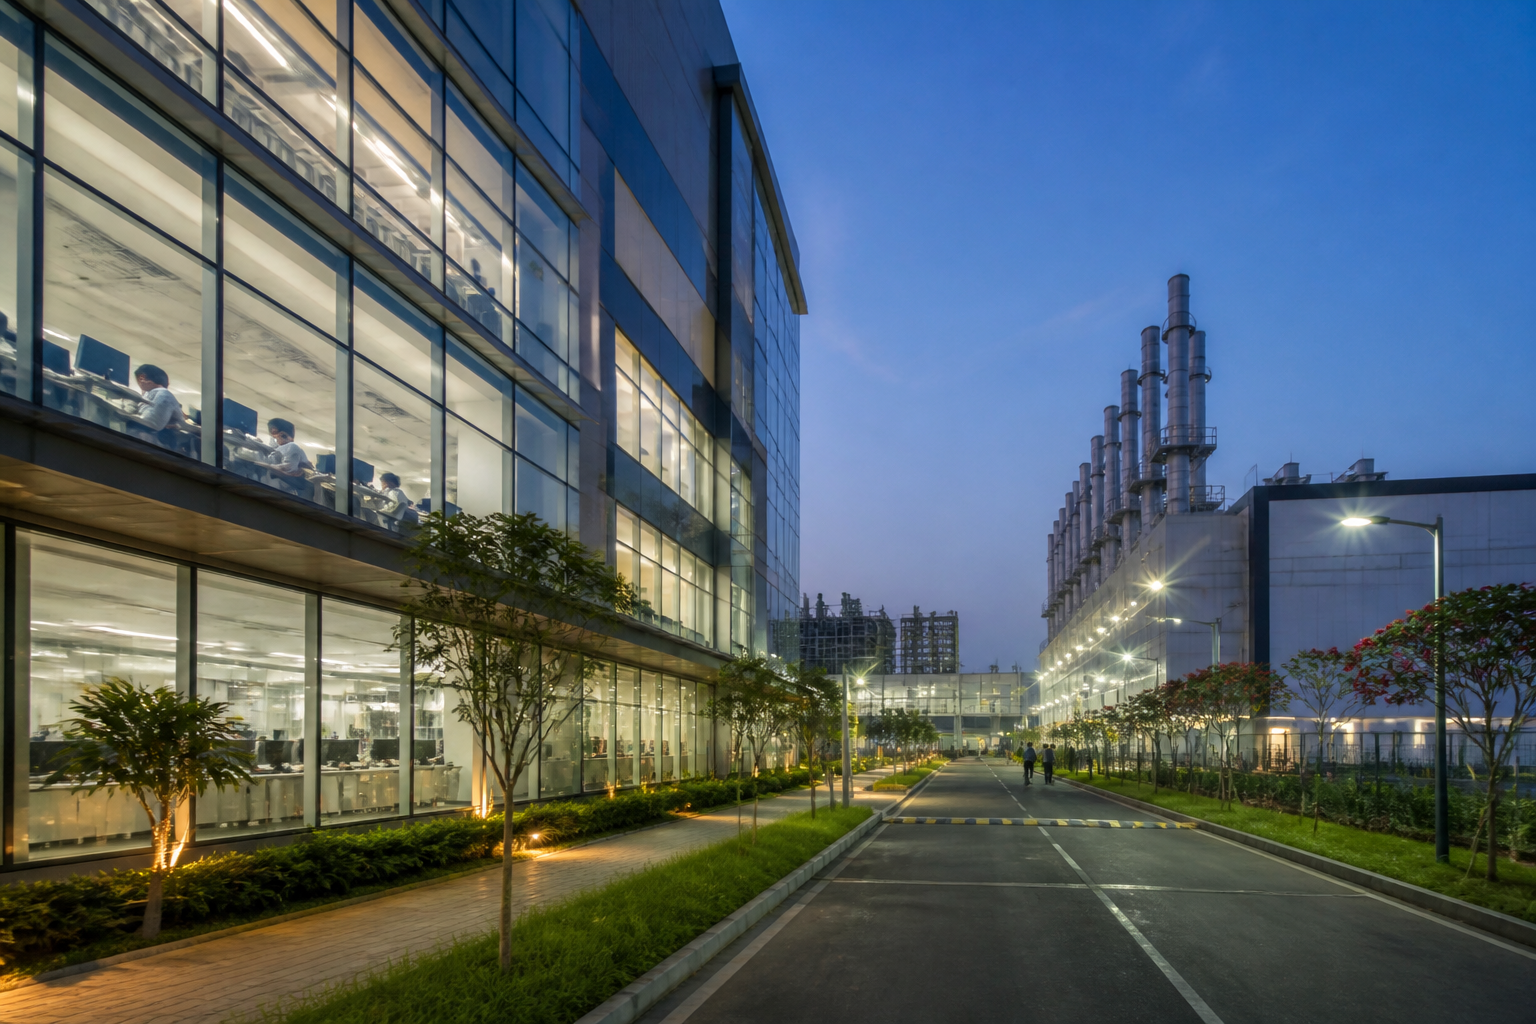
India’s semiconductor strategy is entering a more demanding phase. The country’s ability to benefit from the global chip boom will depend not only on whether it can attract fabrication plants, but also on whether it can connect chip design, manufacturing, equipment and advanced packaging into a wider industrial ecosystem. That shift has direct implications for the specialised urban centres expected to support this industry.
In an interview with ANI, Chip War author and semiconductor expert Chris Miller said India’s Semicon 2.0 strategy should look beyond chip fabrication. He identified chip design, equipment and packaging as areas where India could create greater value, while stressing that deep integration into international semiconductor value chains would be essential for a successful strategy.
The argument challenges a common way of measuring semiconductor ambition: the number of fabs announced or approved. Fabrication is the most visible part of the industry because it involves large facilities, sophisticated utilities and high capital investment. But Miller said governments can place excessive emphasis on this stage while overlooking other segments that generate substantial value, particularly design.
That distinction matters for India because the country already has an established base of chip-design talent. Miller pointed to Hyderabad and Bengaluru as hubs with thousands of chip designers working for Indian and multinational companies. The existing concentration of specialised workers gives India a starting point that is different from building a semiconductor ecosystem entirely from scratch.
The urban consequence is that semiconductor policy cannot be treated only as an industrial-plant issue. Design activity depends on highly skilled labour, research capability, corporate offices and reliable digital and physical infrastructure. Manufacturing and packaging require a different combination of industrial land, utilities, logistics, equipment suppliers and technical workforces. A national strategy that treats all these functions as interchangeable could produce facilities without creating the deeper network that makes an industry resilient.
Miller’s assessment comes as artificial intelligence is changing investment patterns across the global semiconductor sector. He said the expansion of AI has helped companies such as NVIDIA become among the largest players in the industry and has shifted attention towards data-centre applications, new architectures and packaging solutions capable of supporting AI workloads.
This change increases the importance of advanced packaging. Traditionally, packaging was often viewed as a lower-margin and less research-intensive segment than fabrication. Miller said that perception is changing as companies use advanced packaging to improve semiconductor performance. For India, that creates a possible entry point into a part of the value chain where innovation is becoming more important.
The significance of packaging is also spatial. A packaging facility is not simply a smaller version of a fab. It requires its own production systems, technical expertise, supplier relationships and logistics arrangements. If India develops capabilities in this segment, the benefits would depend on how effectively those facilities connect with designers, manufacturers, equipment providers and customers. The location of each activity, and the infrastructure linking them, would become part of the policy question.
The source material does not establish the size, location or timeline of any specific advanced-packaging project in India. It also does not provide investment figures, employment estimates or a detailed account of the government incentives supporting Semicon 2.0. What it does establish is the direction of the strategic debate: India’s semiconductor ambitions are being evaluated across multiple stages of the value chain rather than through fabrication capacity alone.
Miller used South Korea and Taiwan to illustrate the importance of international integration. In his view, successful semiconductor economies first became deeply integrated into global value chains and then invested in specialised areas where they could build technological differentiation. The lesson for India is not simply to replicate the industrial footprint of those economies, but to identify where existing capabilities can connect with global demand.
That approach places India’s cities at the centre of the strategy. Bengaluru and Hyderabad already provide the design base identified by Miller. Manufacturing and packaging, however, may require different urban and regional conditions, including industrial infrastructure, dependable utilities and access to specialised suppliers. The source does not specify which locations are best suited to these functions, but it indicates that the ecosystem will need to extend beyond individual corporate campuses or isolated production sites.
This is where the built environment and industrial policy overlap. Semiconductor facilities are unusually dependent on infrastructure performance. Their needs include advanced production spaces, equipment movement, technical services and the ability to attract and retain specialised workers. The policy challenge is therefore not only to approve projects, but to create places where the different parts of the ecosystem can operate together.
A design-led semiconductor economy also produces a different urban footprint from a fabrication-led one. Design work is likely to reinforce existing technology hubs, while manufacturing and packaging can create new industrial nodes. Equipment and supplier companies may follow both. Without integration, the result could be a collection of disconnected facilities, with design talent in one city, production in another and critical suppliers elsewhere. With stronger integration, these activities could form a more productive network.
Miller’s comments also underline the risk of treating the semiconductor sector as a single industry with a single policy instrument. Fabrication, design, equipment and packaging have different capital requirements, skill profiles and infrastructure needs. They also occupy different positions in the global value chain. A strategy that directs attention or incentives overwhelmingly towards one segment may fail to capture the value created by the others.
The AI-driven shift described by Miller makes that risk more immediate. If demand is moving towards data centres, new chip architectures and high-performance packaging, then the capabilities India builds today must remain connected to changes in how chips are designed and used. The evidence supplied in the interview does not allow a judgement on whether current Indian policy is achieving that balance. It does, however, identify the areas that will determine whether the strategy becomes an ecosystem or remains a set of individual projects.
For policymakers, the central institutional question is coordination. A semiconductor value chain crosses industrial development, urban planning, infrastructure provision, skills and international trade. The supplied material does not detail the administrative responsibilities or funding structure for these areas. But Miller’s argument implies that success will require them to be considered together rather than as separate programmes.
For cities, the question is equally practical. Semiconductor growth will place pressure on the technology and industrial hubs that host it, while creating demand for specialised workspaces, supporting services and reliable connectivity. The source does not quantify this demand, so its eventual urban impact remains uncertain. What is clear is that the industry’s geography will be shaped by more than the availability of land for a fab.
India’s semiconductor opportunity, as presented in the interview, therefore rests on combining its existing design strength with investment in manufacturing, equipment and advanced packaging. The country’s position in the global ecosystem will depend on how effectively those capabilities are connected. The next developments to watch are the specific projects, locations, investments and institutional mechanisms through which Semicon 2.0 converts that broad strategy into functioning industrial and urban networks.
