


South Eastern Coalfields Ltd.’s proposed IPO is more than another large share sale. It is a test of how India’s state-owned energy infrastructure can be brought to public markets without raising fresh capital for the operating company. The Coal India subsidiary has filed a draft prospectus with the Securities and Exchange Board of India, with parent Coal India Ltd. proposing to sell as many as 668.1 million shares.
The offering is entirely an offer for sale. That distinction is central to understanding the transaction. South Eastern Coalfields, or SECL, will not receive new equity proceeds under the structure described in the draft prospectus. Instead, the money raised would come from shares sold by Coal India, which would monetise part of its holding while the operating business continues under its existing ownership framework.
People familiar with the matter have put the potential size of the IPO at as much as $800 million. The figure is not presented in the supplied report as a final issue size, and the eventual offer will depend on the regulatory process, pricing and the terms set out in subsequent filings. The draft prospectus provides the more concrete indicators currently available: the proposed sale of up to 668.1 million shares and the appointment of four book-running lead managers.
Those managers are SBI Capital Markets Ltd., ICICI Securities Ltd., IDBI Capital Markets & Securities Ltd. and Motilal Oswal Investment Advisors Ltd. Their role places the transaction within the formal machinery of a large public issue, from preparing the offer documentation to coordinating the distribution and pricing process. The filing, however, does not by itself establish when the shares will list or what valuation investors will ultimately assign to SECL.
## A monetisation transaction, not a funding round
The structure separates two objectives that are often combined in IPO coverage. A fresh issue is primarily a fund-raising exercise for the company, while an offer for sale allows an existing shareholder to sell part of its stake. In SECL’s case, the disclosed structure points to the second objective. Coal India would be the selling shareholder, and SECL would not receive fresh equity capital from the proposed sale.
That makes the IPO relevant to the management of public-sector assets. Coal India is using the market to create a potential exit or monetisation route for part of its holding in a major subsidiary. The supplied report does not state how much of SECL Coal India would continue to own after the offer, nor does it disclose the proposed price band, valuation or any change to operational control. Those details will be important in later stages of the issue.
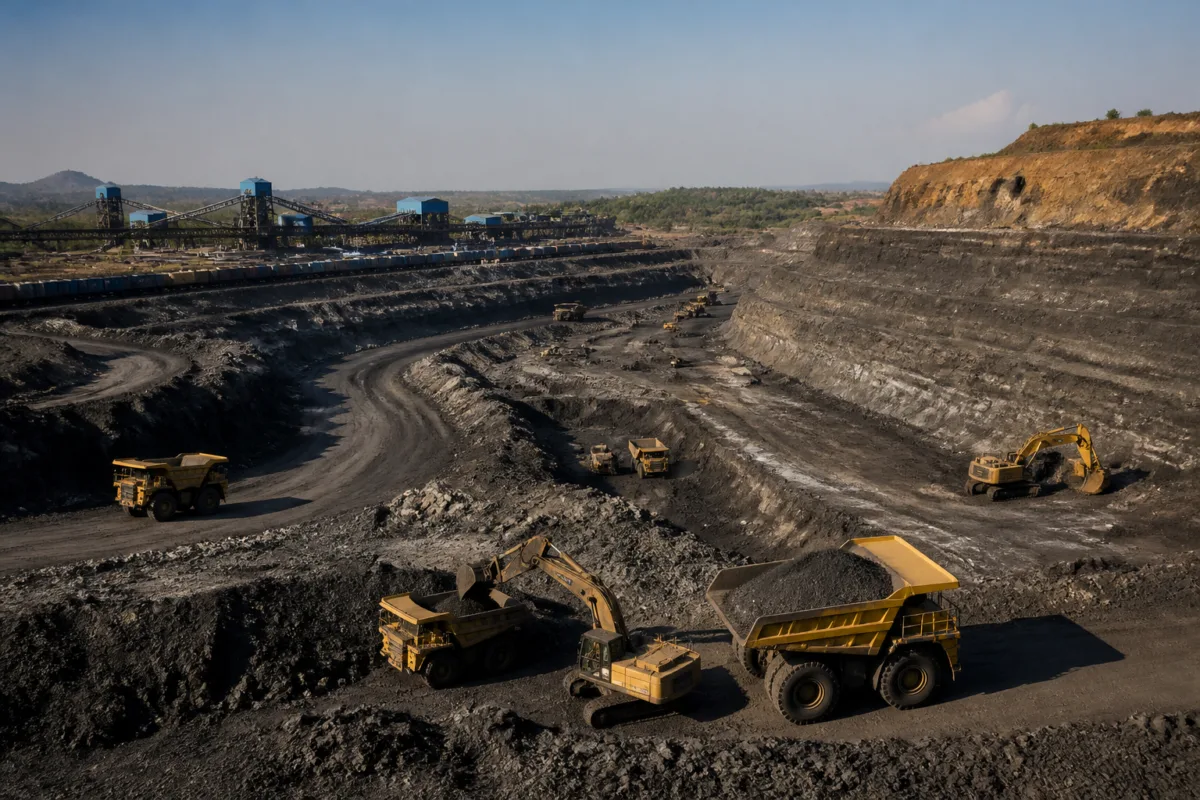
The transaction also illustrates why the quality of the underlying operating business matters even when the IPO is not designed to finance new expansion. SECL operates 60 coal mines across central India, including 35 in Chhattisgarh and 25 in Madhya Pradesh, according to its website. Its geographical footprint gives the proposed listing a direct connection to the production infrastructure that supports India’s energy economy, although the supplied material does not quantify the subsidiary’s share of national coal output or identify its individual customers.
SECL reported revenue of about ₹33,000 crore and net income of ₹4,755 crore for the financial year ended March 31, 2026, according to the prospectus cited by Business Standard. These figures show a large operating base relative to the proposed transaction, but they do not by themselves indicate the company’s valuation. Revenue, profit, reserves, production volumes, costs, liabilities and the final share structure would all influence how the market assesses the business.
## Why the Coal India pipeline matters
SECL is not being brought to market in isolation. Coal India’s other subsidiary, Mahanadi Coalfields Ltd., filed draft paperwork with the regulator in September, according to the report. Taken together, the two filings indicate an effort to take several operating units public rather than relying on a single subsidiary transaction.
That approach can make a large state-owned group more legible to investors. A parent company that owns multiple businesses may be valued on a consolidated basis, while separate listings expose the financial performance and operating profile of individual subsidiaries to the market. The supplied material does not say whether Coal India intends to list additional units beyond SECL and Mahanadi Coalfields, so the broader scale of the programme remains unclear.
The proposed SECL issue is also part of a busy pipeline of Indian share sales, as companies seek to tap domestic capital, the report says. That context matters because a large offering competes for investor attention and liquidity with other issuers. The presence of a deep domestic investor pool may support the issue’s prospects, but the supplied evidence does not provide subscription data, investor categories, comparable valuations or market-demand indicators.
For public-sector transactions, the timing and structure of a sale can also affect how the market reads the government’s approach to ownership. In this case, the disclosed seller is Coal India rather than the central government directly. The available material does not specify the government’s intended ownership level, the policy objective behind the sale or how the proceeds will be used. Those omissions prevent a stronger conclusion about whether the IPO is primarily a disinvestment exercise, a portfolio-management decision or part of a longer-term restructuring plan.
## The infrastructure connection is operational, not promotional
Coal mining is not an urban development project, but SECL’s operations belong to the infrastructure chain that supplies energy to the wider economy. Its mines are spread across Chhattisgarh and Madhya Pradesh, making the company’s performance dependent on large-scale industrial operations, transport links and the movement of a major bulk commodity. The supplied report does not provide details of rail sidings, road networks, evacuation capacity or mine-specific expansion plans, so those aspects cannot be assessed from the filing summary alone.
The same limitation applies to questions about transition risk, environmental liabilities, land acquisition, rehabilitation or the future of coal demand. These are material issues for any assessment of a large coal producer, but the supplied report does not quantify them or provide the relevant disclosures. A responsible reading of the IPO therefore begins with what is established: SECL is a profitable, large-scale subsidiary with 60 mines, and its parent is proposing to sell shares through a public issue.
The offer could nevertheless bring greater public visibility to information that has traditionally been read mainly through the parent company. Once a subsidiary is separately assessed by investors, its revenue, profit and operating disclosures become more important as indicators of business performance. Whether that produces greater transparency will depend on the detail and consistency of the final offer documents, not merely on the filing announcement.
## What remains to be established
The draft prospectus is an important procedural milestone, but it is not the final IPO. The eventual issue size, price band, timing, number of shares actually offered and post-issue ownership will need to be established through the subsequent regulatory and marketing process. The supplied report does not identify an expected listing date or state whether SECL has received final approval to proceed.
The central financial question is also still open. A potential $800 million valuation or fund-raising figure, attributed to people familiar with the matter, cannot be treated as the final outcome. The concrete share count cited from the prospectus is more reliable at this stage, while the final price will determine the gross value of the offer. Since the issue is an offer for sale, the distinction between the value realised by Coal India and capital available to SECL will remain particularly important.
For the urban and infrastructure economy, the filing creates a lens on how essential industrial assets are being separated, disclosed and presented to public investors. It does not yet establish a new mine, a new infrastructure corridor or a fresh investment programme. Its significance lies instead in the ownership and financing architecture around an existing operating network.
The next milestones are the regulatory review of the draft prospectus and the disclosure of final issue terms. Until those are available, the evidence confirms that Coal India has initiated the process of selling up to 668.1 million shares in SECL, while the size, pricing, timing and post-issue ownership of the proposed listing remain to be determined.

