


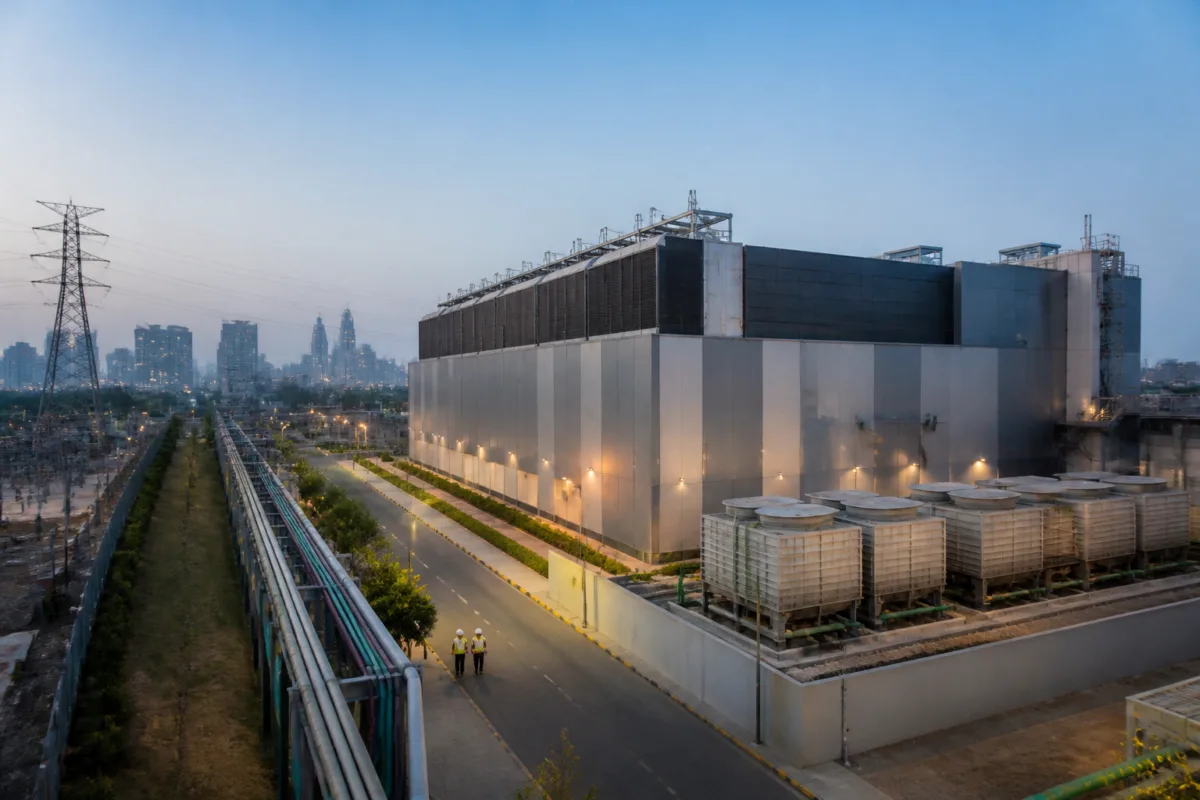
S&P Global Ratings has affirmed Reliance Industries Ltd’s ‘A-’ long-term issuer credit rating, but its assessment also highlights the financial test facing one of India’s largest infrastructure investors: funding data centres, artificial intelligence infrastructure, renewable energy and other emerging businesses while maintaining leverage within limits.
The rating agency has kept the outlook stable, citing resilient earnings, strong cash generation and improved funding flexibility after the listing of digital services subsidiary Jio Platforms Ltd. S&P expects Reliance Industries to sustain above-industry growth in digital services and generate enough cash flow to support elevated capital expenditure.
That combination matters beyond the company’s balance sheet. Reliance’s investment plans span energy, telecommunications, digital services, data centres and new energy. Each of these businesses has a direct or indirect relationship with the built environment: they require industrial facilities, network infrastructure, power supply, data-centre capacity and large-scale capital deployment. The rating therefore provides a window into how a major private-sector group is preparing to finance the next phase of India’s digital and energy infrastructure.
S&P projects consolidated earnings before interest, taxes, depreciation and amortisation, or EBITDA, to grow 19-23 per cent to between ₹2.15 trillion and ₹2.25 trillion in the financial year ending March 2027. The energy-related and digital services businesses are each expected to contribute close to 45 per cent of group EBITDA, indicating the extent to which Reliance’s financial strength now depends on two distinct operating engines.
The first is the oil-to-chemicals business. S&P expects its EBITDA to rise 30-35 per cent in FY27, supported by higher integrated refining margins, lower global crude processing and disruptions to crude oil flows from the Middle East. The agency said crack spreads for gasoline, gasoil and aviation fuel had risen approximately threefold year-on-year in the quarter ended September 30, 2026.
S&P expects Reliance’s oil-to-chemicals EBITDA per barrel to increase to about $18 in FY27 from nearly $14 in FY26. It also expects refining operations to remain at healthy utilisation levels, supported by the company’s complex refining infrastructure and ability to source crude from a wide range of suppliers. These forecasts provide the cash-generation base against which the group’s newer infrastructure commitments are being assessed.
The second engine is digital services. S&P forecasts digital-services EBITDA growth of 12-14 per cent, driven by subscriber additions, higher average revenue per user and the migration of customers to premium plans by Reliance Jio Infocomm amid rising data consumption. The agency’s base case does not assume any further telecom tariff increases.
This distinction is important. The rating affirmation is not based on a single expansion project or an assumed rise in prices. It rests on the expectation that established energy and digital businesses will generate sufficient earnings to support investments whose returns may take longer to emerge. In effect, Reliance’s mature businesses are being treated as the financial platform for its next infrastructure cycle.
The listing of Jio Platforms has strengthened that platform. S&P said the transaction would diversify Reliance’s funding sources and improve access to equity capital, particularly as investment in digital infrastructure increases. The primary issuance of new shares in Jio Platforms raised about ₹30,000 crore in fresh capital, equivalent to around 9 per cent of Reliance’s adjusted debt.
S&P considers the capital infusion modestly credit positive. It estimates that Reliance’s adjusted debt-to-EBITDA ratio could improve to approximately 1.6 times in FY27. The company has stated that it aims to keep reported net debt-to-EBITDA below 1.0 times, while S&P’s methodology translates that into an adjusted ratio of approximately 2.0 times.
The difference between the company’s reported measure and the rating agency’s adjusted measure is significant for infrastructure observers. Large projects can involve obligations that do not immediately appear as conventional corporate borrowing. A rating methodology may therefore examine joint ventures, ownership structures, risk-sharing arrangements and potential support obligations alongside reported debt.
That issue is particularly relevant to Reliance’s proposed data-centre investments through Digital Connexion. S&P said it would assess the financial implications of these joint ventures, including their ownership structures, risk-sharing arrangements and possible financial obligations for Reliance. The agency could include joint-venture debt in its leverage assessment if it believes the company has an incentive to support an associate or joint venture during financial stress.
The rating agency’s caution does not amount to a finding that these projects have weakened Reliance’s credit profile. Rather, it identifies the point at which infrastructure expansion becomes a financial-structure question. Data centres require significant upfront investment in buildings, servers, connectivity, cooling systems and electricity supply. Their credit implications depend not only on the size of the facility but also on who owns the assets, who borrows for them, who bears operating risks and whether the parent is expected to provide support.
S&P expects annual capital expenditure to rise to ₹1.4 trillion-₹1.5 trillion from approximately ₹1 trillion in FY26. Despite the increase, it forecasts the adjusted debt-to-EBITDA ratio to remain between 1.6 and 1.8 times through FY28, supported by earnings growth.
For the urban economy, the significance lies in the infrastructure chain behind digital services. Data consumption is not an abstract online trend. It creates demand for physical data centres, fibre and telecommunications networks, reliable electricity, cooling capacity and industrial land. The supplied rating assessment does not establish the locations, sizes or completion schedules of the proposed facilities, but it confirms that digital infrastructure is becoming an important area of capital allocation for one of India’s largest business groups.
The same applies to artificial intelligence infrastructure. Reliance has announced investments in data centres as part of India’s efforts to develop its AI ecosystem. S&P also identifies artificial intelligence infrastructure, data centres and new energy as important areas of future expansion. However, the agency notes that the investment plans remain at a preliminary stage, even though their eventual scale could be material.
That qualification is central. The rating affirmation reflects the company’s current financial capacity and S&P’s projections; it is not an approval of the commercial performance of every proposed project. The returns from new businesses remain an important factor in the future credit profile, particularly as annual capital expenditure increases and the group continues to diversify beyond its established operations.
Reliance’s financial discipline will therefore be measured against both spending and outcomes. S&P said rating pressure could emerge if the company departs from its financial policy and undertakes aggressive debt-funded investments without corresponding earnings growth. A sustained deterioration in earnings and cash flow that pushes adjusted debt-to-EBITDA materially above 2 times, without a credible recovery path, could lead to a downgrade.
The stable outlook reflects S&P’s expectation that Reliance will maintain strong market positions across its key businesses, expand cash generation and manage elevated capital expenditure while keeping adjusted debt-to-EBITDA below 2 times over the next 12-24 months. The rating’s resilience is thus tied to execution across businesses with different operating cycles: refining, telecommunications, digital infrastructure and new energy.
An upgrade would require stronger business scale and diversification alongside a more conservative financial policy across business cycles. S&P said it could consider an improvement in Reliance’s stand-alone credit profile if adjusted debt-to-EBITDA falls to and remains below 1.5 times. A meaningful contribution from the new-energy business to overall cash flow would also support an improvement.
The assessment also remains linked to India’s sovereign-related credit position. S&P said an upgrade of Reliance’s foreign-currency rating would require an improvement in India’s transfer and convertibility assessment, currently at ‘A-’, as well as a stronger company credit profile.
The immediate evidence, therefore, supports a measured conclusion. Reliance has received a stable rating affirmation because S&P expects earnings growth, cash generation and diversified funding to provide a buffer against its substantial investment programme. But the company’s expanding role in digital and physical infrastructure brings new questions about leverage, joint-venture obligations, capital allocation and the speed at which new businesses generate cash.
The next developments to monitor are the scale and structure of the proposed data-centre investments, the financial obligations attached to joint ventures, the contribution of new energy to cash flow and whether earnings growth keeps pace with the projected rise in capital expenditure. Those factors will determine whether Reliance’s infrastructure ambitions strengthen its credit profile or place greater pressure on it.

