


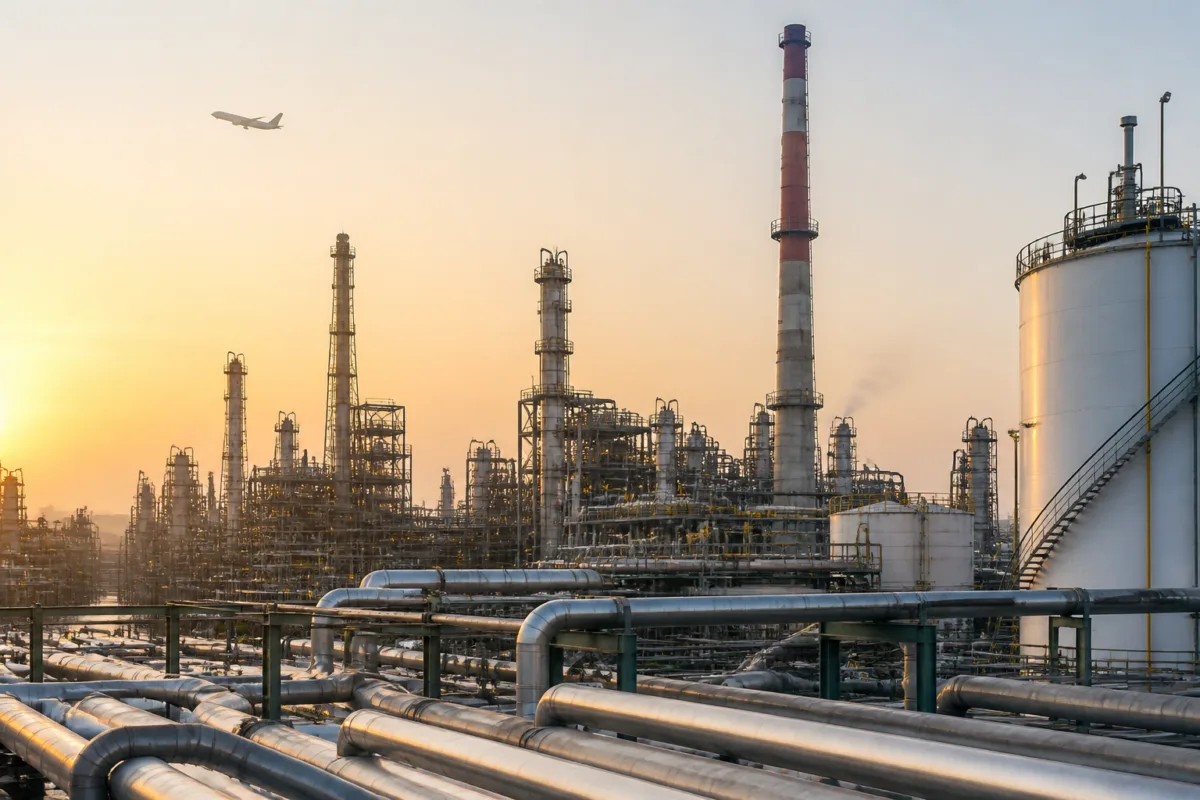
IndianOil’s approval to commercially supply sustainable aviation fuel (SAF) from its Panipat refinery marks a concrete step in India’s effort to build a domestic low-carbon aviation fuel industry. But the development also exposes the harder part of the transition: producing SAF at scale will require dependable feedstock, committed buyers, long-term revenue visibility and public support to narrow the initial cost gap.
The Directorate General of Civil Aviation approved IndianOil’s Panipat SAF production for commercial supply, according to IndianOil Chairman A.S. Sahney, who spoke at the second India Sustainable Aviation Fuel Summit organised by FICCI. Civil Aviation Minister Ram Mohan Naidu Kinjarapu also acknowledged the approval at the event and described the Panipat development as an important achievement for domestic SAF production capabilities.
The facility’s importance lies in the combination of regulatory clearance and existing industrial capacity. IndianOil said the SAF co-processing facility at its Panipat refinery can produce around 30,000 tonnes annually. Sahney said this could meet India’s initial 1 per cent SAF requirement for 2027. The approval therefore moves the project beyond a technology or demonstration stage and towards commercial delivery, while also placing questions of market design and financing at the centre of the policy debate.
The Panipat refinery had received International Sustainability and Carbon Certification under the CORSIA framework for SAF production in August 2025. The certification and subsequent DGCA approval provide the institutional basis for commercial supply described by IndianOil. However, approval alone does not establish a complete SAF market. It enables the product to be supplied, but does not by itself guarantee the feedstock, purchase commitments or financial conditions required for a larger production ecosystem.
That distinction is central to Sahney’s argument. He identified dependable feedstock supplies, bankable demand and measures to bridge the initial cost gap as three priorities for making SAF commercially viable. Each points to a different part of the aviation-fuel chain. Feedstock concerns whether producers can secure the raw materials needed for consistent output. Bankable demand concerns whether airlines or other customers will commit to buying the fuel over a sufficiently long period. The cost gap concerns the difference between SAF and conventional aviation fuel during the early phase of the market.
For project developers and lenders, the demand question is especially important. Sahney said investors would need visibility on future revenues through purchase commitments from customers. In his formulation, future-looking contracts could help projects become bankable by providing greater certainty about potential income. Without that visibility, a producer may have capacity but lack the predictable revenue stream needed to finance additional facilities or expand existing ones.
This places airlines, fuel producers, aircraft manufacturers and government agencies in an interdependent system. SAF production cannot be treated only as a refinery investment because its commercial viability depends on aviation demand and regulatory arrangements. At the same time, airlines cannot rely on a future supply base unless producers can secure financing and feedstock. The market therefore requires coordination across sectors rather than isolated commitments from one industry.
The proposed policy framework reflects this institutional challenge. Earlier reporting by BusinessLine said the Centre’s draft SAF policy envisages viability gap funding, green financing and long-term offtake arrangements, alongside possible tax and duty concessions. These proposals address different barriers: viability gap funding could support projects during the early cost-intensive period, green financing could improve access to capital, and long-term offtake arrangements could create demand visibility.
Yet the framework remains under development. The financial outlay is to be determined by the Petroleum Ministry in coordination with the Civil Aviation Ministry, and the measures described remain proposals. This means the Panipat approval has arrived before the full public support architecture has been settled. The project can supply SAF commercially, but the wider conditions for scaling production still depend on decisions involving two ministries and on how the proposed instruments are eventually designed.
Sahney’s call for a possible production-linked incentive adds another layer to that discussion. He said government support could help contain the final cost of SAF. A production-linked approach would connect assistance to output, while the broader policy proposals also point towards financing support, demand commitments and fiscal measures. The source material does not establish which combination will be adopted, how much funding will be available or how the support will be allocated. Those unresolved details will determine whether the policy is primarily aimed at launching initial projects or building a sustained domestic industry.
The 30,000-tonne annual capacity at Panipat provides a measurable starting point. IndianOil’s assessment that it could meet the initial 1 per cent SAF requirement for 2027 gives the facility a direct connection to the country’s near-term aviation-fuel plans. It also indicates that the immediate policy challenge is not simply to announce a long-term target, but to align available production with a defined requirement and ensure that the fuel can move through commercial arrangements.
The capacity figure also shows why the first phase of SAF development is likely to be shaped by supply-chain reliability as much as by refinery technology. A facility with stated annual capacity still requires regular feedstock and customers prepared to purchase the output. If either side is uncertain, installed capacity may not translate into predictable commercial operations. That is why IndianOil has linked production capability with bankable contracts and dependable inputs rather than presenting regulatory approval as the end of the process.
The company also identified alcohol-to-jet technology and synthetic aviation fuels as opportunities for India. These pathways broaden the industrial question beyond the Panipat co-processing facility. They suggest that the domestic SAF ecosystem could involve multiple technologies and supply arrangements, although the source does not provide capacity, cost or implementation details for these options. Sahney called for collaboration among airlines, aircraft manufacturers, fuel producers and the government as these opportunities are developed.
For urban India, the issue is connected to the future growth and environmental footprint of aviation-linked infrastructure. Airports, airline networks, refineries and logistics systems operate across metropolitan and regional economies. A domestic SAF industry would link those systems more closely to industrial production, agricultural or other feedstock supply chains, financing institutions and central government policy. The immediate Panipat decision is therefore a refinery development, but its implications extend across the infrastructure and economic networks that support air travel.
The evidence currently confirms three things. IndianOil has received DGCA approval to supply SAF commercially from Panipat; the facility has stated annual capacity of around 30,000 tonnes; and the company believes commercial viability requires feedstock security, bankable demand and measures to reduce the initial cost gap. It also confirms that a central support framework is being considered, but that its financial design remains unsettled.
What remains unresolved is equally important: the final structure and size of government support, the nature of customer purchase commitments, the availability of dependable feedstock and the pace at which other SAF technologies can move towards deployment. The next significant developments will therefore not be limited to production approvals. They will include the Centre’s policy decisions, the creation of long-term offtake arrangements and evidence that SAF capacity can be converted into a stable commercial supply chain.

