


Adani Enterprises’ market value has fallen by almost $10 billion since July, turning investor attention from the group’s infrastructure ambitions to the harder question of earnings delivery. The shift matters beyond the stock market: the company is expanding airports, copper production, data-centre equipment manufacturing and city-side developments, all of which require sustained capital, execution and financing capacity.
The company’s shares have declined more than 20% from their July peak, when Adani Enterprises raised $1.6 billion from investors. That retreat followed a 43% rally earlier in the year, as investors responded to the settlement of multiple regulatory and legal cases in India and the United States. The company was due to report its second-quarter earnings on October 28, with analysts expecting it to return to profit after losses linked to the US legal settlement.
The immediate market debate is therefore not whether Adani Enterprises has growth opportunities. Those opportunities are already visible across sectors that are central to India’s urban and industrial expansion. The question is whether the company can convert them into earnings quickly enough to justify the capital committed to them, while managing a rising debt burden and higher financing costs.
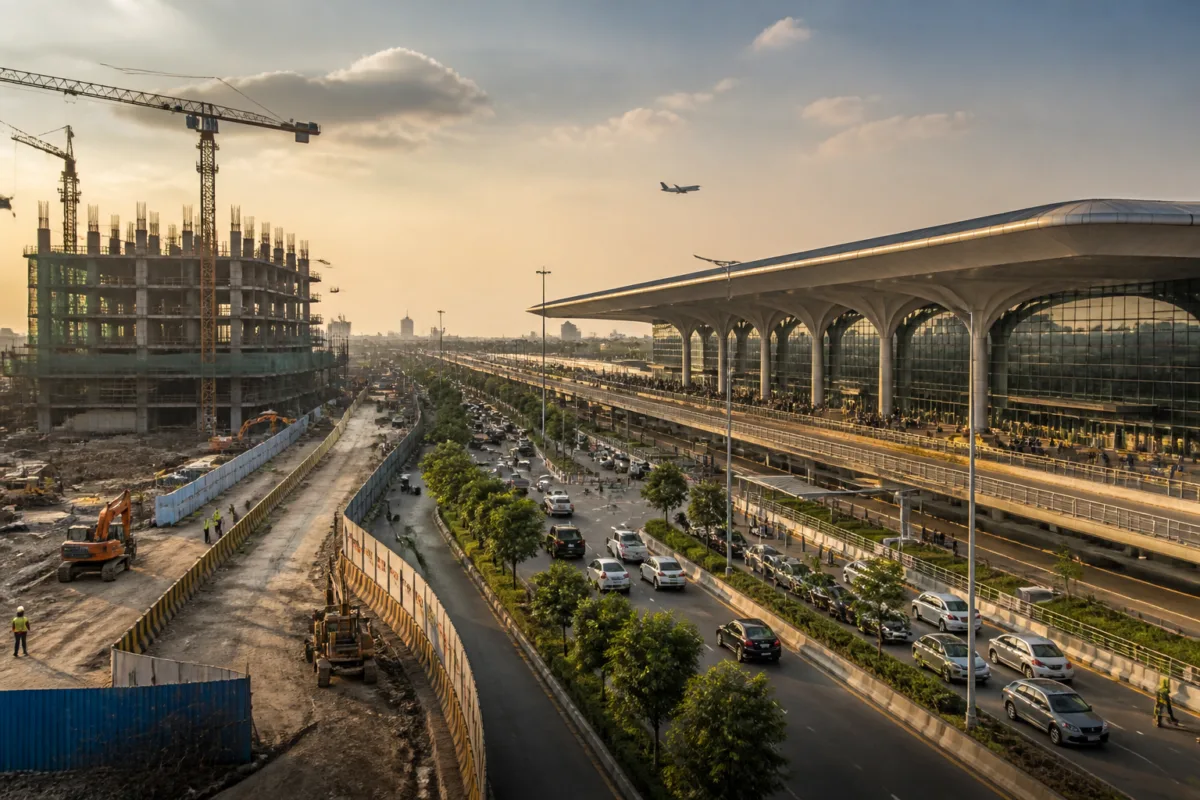
Airports sit at the centre of that test. Adani Enterprises’ airports unit raised about $1 billion in September from investors including Alpha Wave Global, Temasek Holdings and funds managed by BlackRock. The company is also focusing on expansion beyond aviation, including integrated city-side developments across its airport network. Such developments can extend an airport’s economic role beyond terminals and runways, linking passenger infrastructure with commercial, retail and real estate activity. But they also increase the number of projects, approvals, construction schedules and operating assumptions that must work together.
The supplied report does not establish the revenue or profitability contribution of these city-side developments. It does, however, identify them as part of the company’s expansion agenda at a time when investors are demanding evidence of earnings growth. That distinction is important. Infrastructure projects can create long-term urban capacity, but their financial benefits may arrive over different timelines from the capital expenditure needed to build them.
Adani Enterprises’ other emerging businesses face similar execution questions. Analysts are expected to focus on the growth of the airport and copper businesses, as well as the timeline for a joint venture with Jabil to manufacture equipment for artificial intelligence and data centres. The report also identifies copper ramp-up and passenger volumes as issues that could influence the stock’s performance.
These businesses are linked to different parts of the built environment. Airports depend on passenger growth, terminal capacity and associated commercial development. Copper is an industrial input with relevance to power, transport and construction systems, although the supplied material does not provide production targets or project-level timelines. Data-centre equipment manufacturing is connected to the expansion of digital infrastructure, but the report similarly does not establish the venture’s expected output or earnings contribution.
The common factor is that each business is still being judged on its ability to move from investment and expansion to measurable operating performance. Gary Tan, a portfolio manager at Allspring Global Investments, said the earlier rally had priced in stronger institutional support, fresh capital and faster earnings growth across Adani Enterprises’ emerging businesses. He said investors had now shifted their focus from growth potential to earnings delivery.
That change in focus is reflected in the company’s debt position. Gross debt stood at ₹97,620 crore, or $10.3 billion, as of June, according to the company’s earnings presentation. The figure was almost 13% higher than a year earlier. The rise creates a direct link between infrastructure ambition and financial pressure: the more capital-intensive the expansion programme, the more important borrowing costs and project cash flows become.
The report notes concerns about financing costs during a period of rising bond yields. It does not provide a consolidated project-by-project breakdown of debt, nor does it state how much of the gross debt is allocated to airports, copper, the Jabil venture or city-side developments. That limitation prevents a precise assessment of which business is carrying the greatest financing burden. It does show, however, that the company is pursuing expansion while its total gross debt is increasing.
For urban infrastructure, the institutional question is not simply whether a large conglomerate’s shares rise or fall. Airport expansion and city-side development involve public-facing assets, long construction cycles and multiple relationships with authorities, lenders, operators and private investors. Their progress can influence mobility, commercial land use and the development pattern around airport corridors. Their financial structure can also affect the pace at which planned capacity is built.
The airport unit’s separate fundraising indicates that investors may be willing to support specific infrastructure platforms even while reassessing the flagship company. Alpha Wave Global, Temasek and BlackRock-managed funds participated in the airport transaction, according to the report. That funding may strengthen the unit’s ability to pursue its plans, but the supplied material does not specify the use of proceeds or the conditions attached to the investment.
The market’s reassessment also reflects a broader distinction between institutional confidence and operating proof. Capital Group, Goldman Sachs and SBI Funds Management participated in Adani Enterprises’ July stock sale. At least three brokerages, including Morgan Stanley, had initiated coverage with buy calls before the stock fell from its July high, and none had changed its recommendation at the time of the report. Yet the decline shows that positive recommendations do not remove the need for project execution and earnings confirmation.
GQG Partners provides a different signal. The long-time Adani backer reduced its holding in Adani Enterprises to 1.82% at the end of September from 3.9% in March, according to regulatory filings. Rajiv Jain, the fund’s co-founder, said the reduction was intended to keep the position size reasonable after the stock appreciated. He also said there had been zero decline in the firm’s enthusiasm for infrastructure bets in India because demand remained unabated.
That statement captures the tension facing infrastructure developers and investors. Demand for airports, industrial capacity and digital infrastructure may remain strong, but demand alone does not guarantee that a particular project will generate earnings on the expected schedule. Delivery depends on land, approvals, procurement, construction, operations, financing and the ability to maintain demand through the investment cycle.
The wider market backdrop has made the reset more visible. The Nifty 50 had fallen almost 13% during the year, heading for its first annual decline since 2015, according to the report. Adani Enterprises’ retreat therefore cannot be separated entirely from broader market weakness. At the same time, its earlier rally was closely associated with the removal of regulatory overhangs after settlements involving probes by India’s securities regulator and the US Treasury Department.
This sequence matters because the company’s valuation has been influenced by both institutional confidence and the perceived reduction of legal and regulatory risk. Once that overhang eased, investors looked more closely at the operational milestones needed to support the valuation. The market’s current concern is consequently less about whether Adani Enterprises can announce large projects and more about whether those projects can produce transparent, timely and sufficiently strong earnings.
The company’s forthcoming financial disclosures are therefore important for more than their effect on the share price. They are expected to provide signals on airport passenger volumes, the copper business’s ramp-up, the timeline for the Jabil venture and the financial implications of the broader expansion programme. The report does not provide the results themselves, so the actual performance of these businesses remains outside the evidence available here.
The larger urban question is how India’s infrastructure build-out is financed when major platforms combine public-facing assets, industrial ventures and real estate-linked development. Integrated airport districts, new terminals and data-centre supply chains can support urban growth, but they also require investors and institutions to track debt, delivery schedules and operating performance alongside headline capital commitments.
Adani Enterprises’ $10 billion market-value loss does not by itself establish that its infrastructure plans are failing. Nor does the company’s earlier rally prove that those plans will deliver the expected returns. What the evidence confirms is a sharper accountability phase: the company is carrying higher gross debt, investors have lowered their tolerance for delayed earnings, and its airports, copper, Jabil and city-side development businesses now face closer scrutiny. The next material indicators are the company’s earnings, passenger volumes, copper ramp-up, Jabil timeline and any guidance on financing and project execution.

