


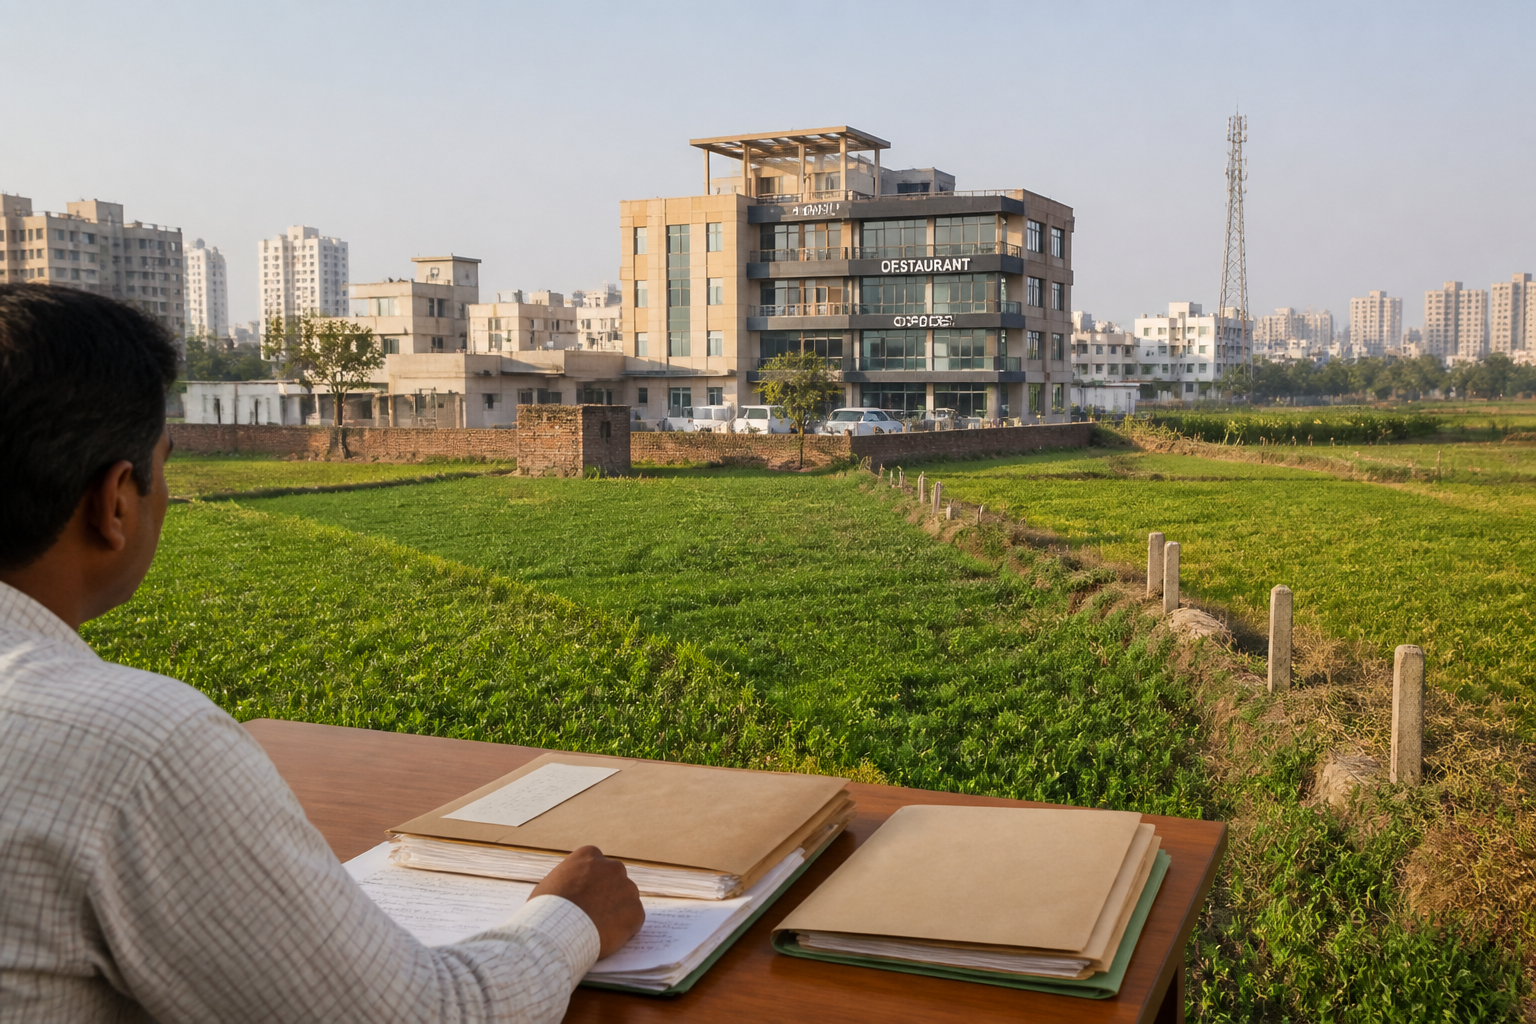
The Income Tax Appellate Tribunal (ITAT), Chandigarh, has given substantial relief to a Panchkula resident whose claim for long-term capital gains (LTCG) exemptions was challenged after he sold ancestral agricultural land for Rs 8 crore. The ruling turned not simply on where the taxpayer owned property, but on what that property was actually used for and what the evidence established about replacement land.
The case illustrates a recurring difficulty in property taxation: legal treatment can depend on the difference between ownership and use. A building may be owned by a taxpayer, but that does not automatically make it a residential house for every provision of the Income-tax Act. Similarly, agricultural land located within an urban area may not lose its character solely because of its geographical setting. In this case, the tribunal relied on physical verification and documentary evidence to examine those distinctions.
According to the details reported by the Times of India, the taxpayer sold his family’s ancestral agricultural land in a village in 2017 for Rs 8 crore. After accounting for certain expenses, he declared LTCG of Rs 7.73 crore. He claimed exemptions of Rs 2.64 crore under Section 54F and Rs 3.73 crore under Section 54B.
Section 54F concerns investment in a residential house after the sale of a long-term capital asset other than a residential house. One of its conditions is that the taxpayer should not own more than one residential house, apart from the new property, on the date of transfer of the original asset. Section 54B concerns the sale of agricultural land and permits relief when the gains are reinvested in qualifying agricultural land within the prescribed period.
The Assessing Officer rejected both claims on the basis of the documents submitted by the taxpayer. This resulted in total additions of approximately Rs 6.36 crore. The taxpayer challenged the assessment before the Commissioner of Income Tax (Appeals), or CIT(A). The appellate authority allowed partial relief on the Section 54B claim but rejected the Section 54F exemption.
The Section 54F dispute centred on a property in Dhakoli, Zirakpur. The CIT(A) treated the property as a residential house and concluded that the taxpayer owned more than one residential property when he sold the original asset. The taxpayer argued that the property was being used commercially: it housed his restaurant and office.
That distinction became decisive before the ITAT. The tribunal directed the Assessing Officer to conduct physical verification of the property and establish its actual nature. The resulting remand report confirmed that the property was located in a commercial zone and was being used for commercial activities. On that factual basis, the tribunal concluded that it could not be classified as a residential house merely for the purpose of restricting the Section 54F claim.
Chartered Accountant Suresh Surana, quoted in the report, explained the distinction by noting that the restriction under Section 54F concerns ownership of residential houses, not every type of immovable property owned by a taxpayer. The tribunal consequently deleted the disallowance of Rs 2.64 crore under Section 54F, subject to fulfilment of the remaining statutory requirements.
The ruling therefore placed the emphasis on the actual use and character of the Dhakoli property rather than on a broad assumption based on ownership. That is important in a property market where the same building may combine residential, commercial, office or mixed-use functions. The case does not establish that every property described as commercial will qualify for an exemption. Instead, the reported decision shows that the classification must be supported by facts and assessed against the specific statutory condition in dispute.
The second issue concerned the agricultural land purchased after the sale. The taxpayer produced purchase deeds showing investments of Rs 80 lakh and Rs 45 lakh in 2018 for agricultural properties in Chhat and Sanoli villages. The physical inspection ordered by the tribunal verified both the transactions and the agricultural character of the properties, according to the report.
The Income Tax Department questioned the Section 54B claim because two of the properties were located within an urban area. The tribunal did not consider urban location, by itself, sufficient to deny the exemption. It allowed the deduction to the extent of the qualifying investment established through the purchase deeds and other supporting material.
This part of the case separates location from land use. Urban expansion frequently brings agricultural parcels within or near built-up areas, creating a difficult administrative question: whether the land’s tax treatment should be determined by its location, its recorded description, its actual use or a combination of these factors. The ITAT’s reported approach was that the mere fact of being situated in an urban area could not independently defeat the Section 54B claim when the evidence supported the agricultural nature of the replacement properties.
Section 54B relief is linked to the use of agricultural land during the two years immediately before its sale and to reinvestment in another agricultural property within two years. The benefit is limited to the amount invested in the replacement land. If the newly acquired land is sold within three years, the earlier benefit is effectively reversed through a reduction in its cost of acquisition.
The report also notes that the Income-tax Act, 2025, came into effect from April 1, 2026, and that the corresponding provision is now covered under Section 83 of the new law. The tribunal case, however, arose from the 2017 sale and the statutory provisions discussed in the reported proceedings. The applicable legal provision must therefore be read in the context of the relevant assessment year and transaction date.
The institutional significance of the ruling lies in the method used to resolve the dispute. Rather than deciding the property’s character only from the taxpayer’s return or from an assumption about its location, the tribunal sought an on-ground verification. The Assessing Officer’s remand report then became important evidence in determining whether the Dhakoli property was commercial and whether the replacement parcels were agricultural.
That approach also shows why property-related tax claims depend heavily on records. Purchase deeds, evidence of use, zoning or location details, and physical verification can affect whether a taxpayer satisfies the conditions of a tax exemption. A claim based only on the broad description of a property may face difficulty if the surrounding evidence points in another direction. Conversely, a taxpayer may receive relief when official verification confirms the factual basis of the claim.
The case should not be read as a general exemption for all sales of agricultural land or purchases of property in urban areas. The Section 54B relief was allowed only to the extent of qualifying investment substantiated by the available evidence. The Section 54F relief was also linked to the finding that the additional property was commercial rather than residential, and remained subject to the other statutory requirements.
For property owners and tax administrators, the larger question is how urbanisation changes the character of land and buildings faster than administrative categories do. A former agricultural parcel can become part of an expanding urban region, while a property recorded or owned by an individual can function as a commercial establishment. The ruling, as reported, places the burden of decision-making on the specific facts rather than on a single label.
The ITAT Chandigarh decision therefore offers a narrow but important lesson in property taxation: eligibility for LTCG relief cannot be determined solely by ownership, location or an entry in a tax return. The actual use of a building, the character of replacement land and the documentary record all matter. The reported outcome also underlines that physical verification by tax authorities can materially alter the assessment when the central dispute is factual rather than purely interpretive.

