


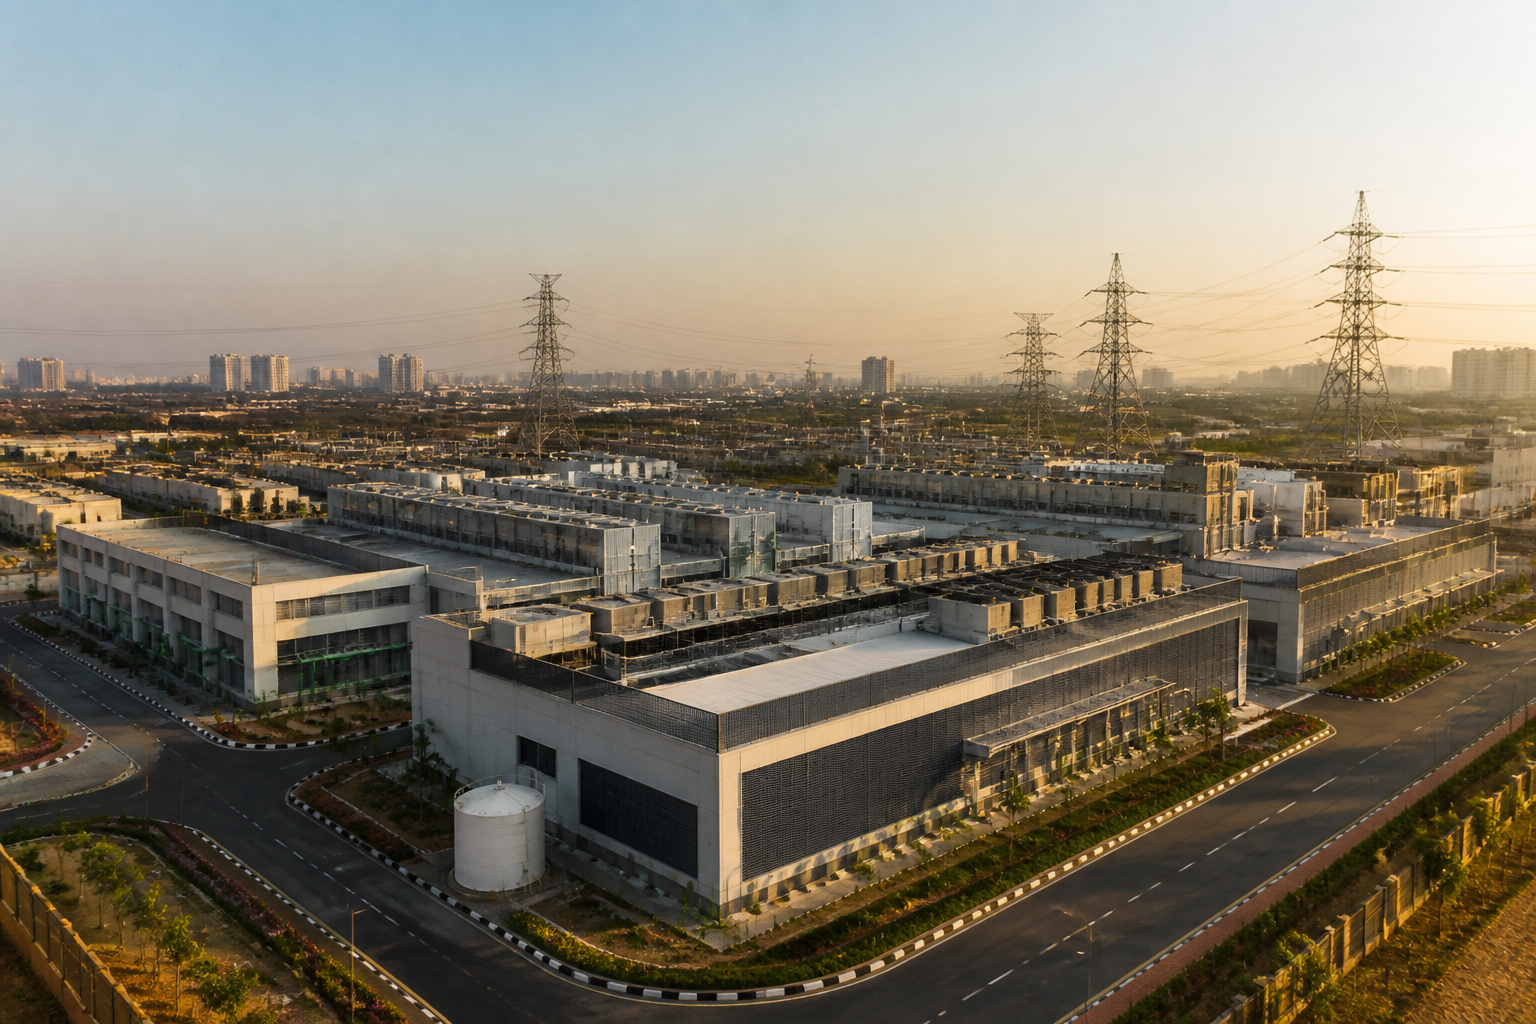
Telangana’s position as the state with India’s most attractive data centre policy package, according to an S&P Global Energy assessment, reveals how the competition for digital infrastructure is moving beyond tax concessions. States are now competing over electricity, land, capital support, regulatory clearances and the ability to provide reliable operating conditions for facilities that are becoming a distinct infrastructure asset class.
The Data Center Policy Attractiveness India index evaluated 19 policies across 11 states. The policies covered information technology, information technology-enabled services, data centres and global capability centres, and were enacted since 2016. S&P Global Energy assessed them across four broad categories: electricity; land and capital; operational and technical support; and regulatory and ease-of-doing-business frameworks.
The result was a closely contested top tier. Telangana led the overall assessment, while Maharashtra and Uttar Pradesh were described as having balanced frameworks covering power, infrastructure, capital and regulatory mechanisms. Gujarat stood out for electricity-related and ease-of-doing-business measures aimed at attracting hyperscale facilities. The four leading states were placed at scores of around 50 out of 100, indicating that the competition is spread across different policy strengths rather than dominated by one state on every measure.
That distinction matters because a data centre is not simply another commercial building. Its viability depends on a continuous supply of electricity, cooling systems, connectivity, land, construction capacity and regulatory approvals. A state can offer capital incentives, but those incentives have limited value if power supply is unreliable, land assembly is slow or approvals remain fragmented. Conversely, strong electricity incentives may not be enough if a project cannot secure suitable land or obtain operational clearances within a predictable timeframe.
The index therefore provides a useful picture of what states are trying to assemble. Telangana’s leading position is linked in the report to a strong combination of electricity and regulatory incentives. Maharashtra and Uttar Pradesh have formulated wider packages, while Gujarat has concentrated on electricity and ease-of-doing-business measures. These approaches reflect different interpretations of what data centre investors need, even as all four states compete for the same expanding market.
The second group, scoring between 42 and 45, includes Odisha, Haryana, Andhra Pradesh and Karnataka. Andhra Pradesh leads this group on land and capital support. Karnataka has notable ease-of-doing-business measures, including an Essential Services Maintenance Act cushion. Odisha and Haryana have adopted strategies that span the project life cycle, rather than focusing on a single incentive category.
A third cluster, scoring between 30 and 40, comprises Rajasthan, Tamil Nadu and West Bengal. Tamil Nadu performs strongly on capital expenditure support, including captive renewable energy infrastructure, but it and West Bengal score lower on electricity-sector incentives. The contrast shows why policy competition cannot be evaluated only through the size of a subsidy or the presence of a sector-specific scheme. The operating environment must also address the infrastructure costs that continue after construction.
The electricity question is becoming more important because India’s data centre expansion is expected to be substantial. Existing capacity from enterprise, colocation and dedicated facilities stands at about 1.5 gigawatts, according to the report. A further 5 GW has already been committed, while another 6-7 GW has been announced or is in the early planning stages. Citing official parliamentary projections, S&P Global Energy said total capacity could rise to 26.3 GW by the 2031-32 financial year.
Those figures change the scale of the policy challenge. The issue is no longer whether individual states can attract a handful of facilities. It is whether power systems, land markets, urban infrastructure and regulatory institutions can absorb a much larger concentration of facilities over the next decade. The report estimates that total electricity demand from Indian data centres, including heating, ventilation, air conditioning and operational loads, will grow at a compound annual growth rate of 18 per cent between 2025 and 2035.
For cities and urban regions, this expansion creates a specific infrastructure relationship. Data centres may have a relatively limited direct workforce compared with other large industrial projects, but they require substantial physical systems. High-capacity electricity connections, backup systems, cooling infrastructure, roads, telecommunications networks and secure sites all have to be planned and delivered. Their effects can therefore extend beyond the boundary of a single facility, particularly where multiple projects are concentrated in the same state or metropolitan region.
The S&P assessment also places competitive federalism at the centre of the sector’s expansion. States are offering targeted fiscal incentives, streamlined clearances and access to reliable clean power. This competition can help identify and remove institutional bottlenecks, but it also means that states are shaping long-term infrastructure commitments through packages that combine public support with private investment.
The design of those packages is especially important because the four policy categories are connected. Land and capital support can reduce the initial cost of a project. Electricity incentives can affect recurring operating costs. Technical and operational support can influence the time required to establish a facility. Regulatory and ease-of-doing-business measures can determine whether the project moves from an announcement to construction and then to operation.
The report’s state-level results suggest that there is no single template. Andhra Pradesh’s strength in land and capital support differs from Karnataka’s regulatory approach. Tamil Nadu’s capital expenditure support, including captive renewable energy infrastructure, differs from Gujarat’s electricity and ease-of-doing-business focus. Telangana’s overall lead is associated with the combination of electricity and regulatory incentives, while Maharashtra and Uttar Pradesh have pursued broader packages.
This variety also points to an administrative question: how will governments measure whether policy incentives are producing functioning capacity rather than only attracting announcements? The supplied assessment records committed, announced and early-stage capacity separately, which is significant because these categories represent different stages of project certainty. A planned facility still requires land, approvals, financing, construction and power connections before it becomes operational capacity.
The energy implications are equally central. Data centres require electricity not only for servers but also for cooling and related operational systems. As demand grows, the quality, reliability and source of that power become part of the competitiveness equation. S&P Global Energy’s reference to reliable clean power indicates that states are increasingly treating energy availability and emissions considerations as linked elements of the investment proposition.
For urban policymakers, the expanding sector raises a further planning issue: where should these facilities be located, and what supporting infrastructure should be reserved for them? The source material does not identify specific city-level clusters or compare local planning rules, so the precise geographic consequences are not established here. It does, however, show that state policy is being designed around infrastructure requirements that reach into land, electricity, transport and regulatory administration.
The central evidence is clear. India’s data centre market is expanding from an existing base of about 1.5 GW towards a projected 26.3 GW by 2031-32, while states are competing through increasingly differentiated policy packages. Telangana leads the S&P Global Energy assessment, but Gujarat, Maharashtra and Uttar Pradesh remain close in the top cluster, and other states have specific advantages in land, capital, regulatory support or renewable-energy infrastructure.
What remains uncertain is how much of the announced and planned capacity will become operational, how states will manage the associated electricity demand, and whether incentive packages will be matched by delivery capacity inside public agencies. Those questions will determine whether India’s policy race produces durable digital infrastructure or primarily a larger pipeline of proposals.
