


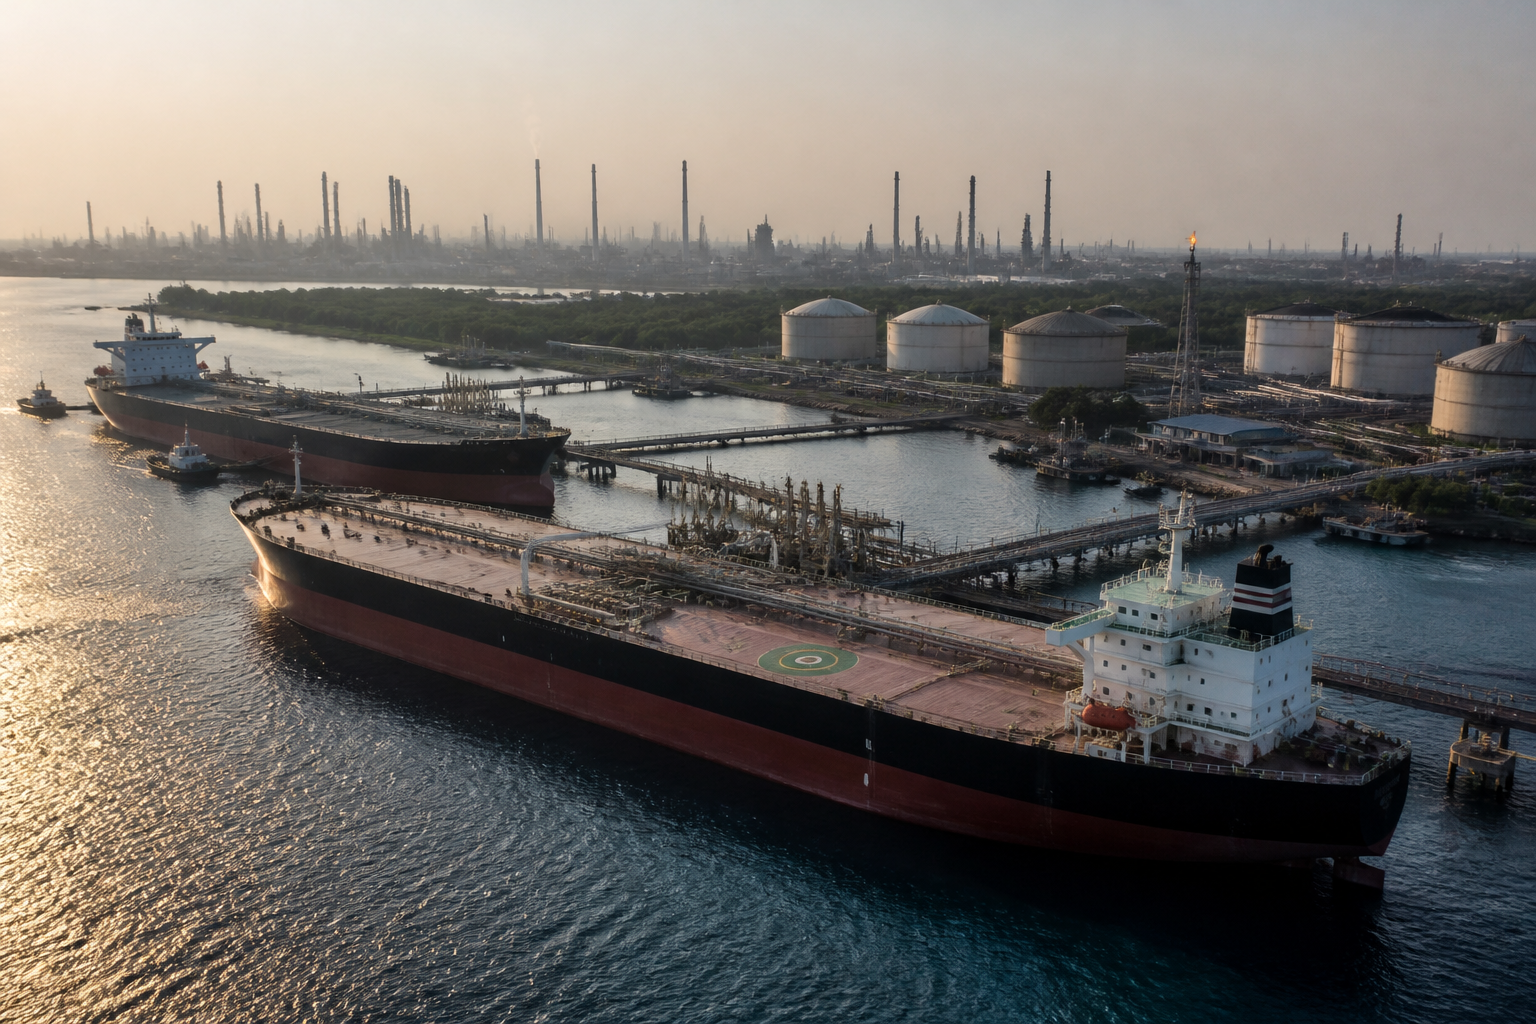
India’s Venezuela oil imports are set to more than double in October as refiners respond to higher Russian crude costs and growing risks linked to sanctions and punitive tariffs. The shift does not yet represent a break from Russia, which remains India’s largest crude supplier, but it reveals how quickly procurement patterns can change when price, freight and geopolitical risk begin to move in the same direction.
The reported increase comes as crude supply routes face renewed pressure from tensions in the Middle East. The disruption has raised costs for energy products in India, including petrol, diesel, LPG and CNG, even though domestic energy supplies remain stable. India has responded by sourcing crude from a wider group of producers, including Russia, Venezuela and the United States.
That strategy is not new in principle. Indian refiners have consistently sought supplies from countries offering commercially attractive crude. What has changed is the relative balance between price advantage and risk. Russian crude, which became a major component of India’s import basket, is now facing higher prices. At the same time, refiners are becoming more cautious about the possible consequences of US sanctions and punitive tariffs associated with Russian purchases.
Against that backdrop, Venezuelan crude has re-entered the procurement picture at a larger scale. Bloomberg, as cited in the report, said India’s imports from Venezuela were expected to reach about 465,000 barrels per day in October, compared with 196,000 barrels per day in September. If scheduled cargoes arrive on time, October’s volume would be the highest since December 2019. The report also cautions that the final volume could be lower because some shipments may not be unloaded before the end of the month.
The distinction between scheduled supply and delivered supply is important. Sumit Ritolia, a senior manager at Kpler, estimated that the average delivery during October would be closer to 350,000 barrels per day because some vessels would not be able to discharge their cargo before the month ended. The two figures therefore describe different stages of the supply chain: cargoes expected to reach India and the quantity likely to be physically delivered during the month.
This difference also shows why crude-import data must be read alongside shipping movements. According to vessel-tracking information cited in the report, all Venezuelan ships currently headed for India identify Sikka port in Gujarat as their destination. Sikka serves Reliance Industries’ Jamnagar refinery complex, described in the report as the world’s largest refining centre. At least two tankers were expected to reach India’s western coast on October 31.
The concentration of the reported Venezuelan cargoes around Sikka highlights the role of port and refinery infrastructure in determining how quickly global supply changes can reach Indian markets. A change in sourcing is not complete when a refinery agrees to buy crude. Vessels must be scheduled, ports must receive them, and refineries must process the specific crude grades within their operating systems. The available report does not provide details of refinery yields, cargo values or the exact commercial terms, but it does show that shipping and discharge schedules will influence the final import numbers.
India’s dependence on Russian crude has already begun to fall in proportional terms. Kpler data cited by Aaj Tak Business shows Russia’s share of India’s crude imports declining from 56% in July to about 35% in September. Russia remains the country’s largest supplier, but the reduction indicates that the import basket is becoming more distributed across producing countries.
The change has two dimensions. The first is commercial. The report says Russian Urals crude has become more expensive, with prices for crude arriving from the Baltic Sea reaching their highest level since the beginning of the Ukraine war. If the discount that made Russian crude attractive narrows, refiners have a stronger incentive to compare it with supplies from Venezuela and other producers.
The second dimension is regulatory and geopolitical. Indian refiners are reportedly becoming more cautious about Russian purchases because of the threat of US sanctions and punitive tariffs. That does not mean Russian crude has disappeared from the Indian market. It means that the cost calculation now includes more than the headline price of a barrel. Potential restrictions, compliance exposure and the risk of future disruption can influence procurement decisions even when the underlying demand for crude remains unchanged.
Venezuela’s return to the supply mix is linked to a separate policy change. The report says India resumed Venezuelan crude imports in February after an interruption of about one year, following a relaxation of US restrictions on Venezuelan crude exports. This sequence matters because the expansion of imports has been enabled not only by market prices but also by the policy environment governing access to the oil.
That makes the supply shift more conditional than a simple substitution of one producer for another. Venezuelan crude may offer a price advantage, but the ability of Indian refiners to continue buying it depends on the continuation of the applicable export and sanctions framework. The supplied report does not establish how long the current conditions will last or whether October’s higher shipments will become a sustained trend.
The pattern also exposes the institutional mechanics behind India’s energy security. The country’s response to supply stress is not described as reliance on one replacement supplier. Instead, crude is being sourced from several countries while refiners reassess the balance between cost and risk. This diversification can help maintain physical supply when one route becomes more expensive or uncertain, but it also requires ports, tankers and refineries to handle changing trade flows.
The effects extend beyond crude procurement. The report links Middle East supply disruption and higher crude costs with increases in petrol, diesel, LPG and CNG prices in India, although it does not provide the size or timing of those increases. This connection places crude sourcing within a broader urban system. Transport costs, household energy expenses and the operating costs of commercial fleets are all exposed to changes in energy prices, even when fuel availability remains stable.
For cities, the immediate issue is therefore not only whether India can secure enough crude. It is whether procurement changes can limit the transmission of global supply shocks into household and mobility costs. The material supplied does not provide enough evidence to measure that impact, but it confirms the mechanism: international crude prices and shipping conditions influence refinery input costs, which can affect domestic fuel markets.
The reported numbers show a fast-moving adjustment. Venezuelan imports are estimated to rise from 196,000 barrels per day in September to a possible 465,000 barrels per day in October, while the more conservative delivery estimate is around 350,000 barrels per day. Over the same period, Russia’s share of India’s crude imports is reported to have fallen from 56% in July to about 35% in September. These figures do not prove that Venezuelan crude has replaced Russian crude barrel for barrel, but they do show that India’s sourcing mix is changing as the relative economics and risks shift.
Several uncertainties remain. The October Venezuelan figure depends on vessels reaching port and unloading on schedule. Some cargoes may not arrive before the end of the month, reducing the final delivered volume. The report also does not specify how much of the change is driven by refinery-specific requirements, the discount on Venezuelan crude, sanctions-related considerations or the cost of alternative supplies.
What the evidence confirms is narrower but significant: India is still buying the most crude from Russia, yet Russian supply is losing share while Venezuelan shipments rise. The change is being shaped by price, shipping schedules, export restrictions and sanctions risk at the same time. The next measurable test will be whether the October cargoes are delivered as scheduled and whether the expanded Venezuelan flow continues beyond the month.
