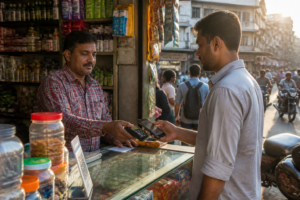
The National Payments Corporation of India’s clarification on GST applied to the Unified Payments Interface merchant discount rate is meant to settle a growing concern: whether digital payments are about to become more expensive for India’s smallest businesses. The answer supplied by NPCI is narrower than the headlines suggest. GST would apply to the merchant discount rate, or MDR, and not to the value of the UPI transaction itself. Yet the policy still exposes a more important change in India’s digital commerce system: high-value merchant payments are becoming a larger part of UPI activity, creating a new cost and tax question for businesses that were accustomed to zero-MDR payments.
According to the clarification reported by Aaj Tak Business, MDR will apply from October 15 to person-to-merchant transactions above ₹2,000. The standard rate cited is 0.4%, subject to a maximum of ₹300. For railway, telecom services, insurance and fuel, a concessional MDR of ₹5 will apply to transactions above ₹2,000. MDR is described as a service fee for payment processing and settlement, generally paid by larger merchants.
The distinction between the transaction value and the payment service fee is central. On a ₹10,000 merchant transaction, an MDR of 0.4% would amount to ₹40. The 18% GST would then apply to the ₹40 MDR, producing a GST amount of ₹7.20. It would not apply to the full ₹10,000 paid by the customer. This means the immediate tax base is the payment service, not the price of the goods or services sold through UPI.
That clarification addresses one part of the concern, but it does not make the question irrelevant for every merchant. The actual effect depends on who pays the MDR, whether the merchant is registered under GST, the nature of the goods or services sold and whether the business can claim input tax credit. A registered merchant with an output GST liability may claim input tax credit on the GST charged on MDR and set it against that liability, according to the explanation cited in the report.
The benefit is not universal. Businesses selling tax-free goods or services may not be able to use the credit in the same way. For them, GST paid on MDR could remain a cost. The distinction matters because the policy does not distribute its effects only according to transaction size. Two merchants processing payments of a similar value could experience different financial outcomes depending on their tax status and business category.
NPCI’s wider argument is that most UPI merchant transactions will remain outside the MDR framework. Transactions up to ₹2,000 will continue to carry zero MDR, and NPCI says that more than 96% of the total volume of UPI merchant transactions falls within this range. The organisation has also said that merchants receiving up to ₹1 lakh a month through UPI do not need to pay MDR.
If these thresholds remain the dominant pattern, the policy will not create a broad-based charge on the neighbourhood shops and small businesses that rely on low-value digital payments. A customer buying a modest grocery order, making a routine local payment or paying for a low-value service would continue to use a zero-MDR transaction under the framework described by NPCI. This is the basis for the organisation’s assertion that concerns about a widespread additional burden on small merchants are misplaced.
But the volume figure does not tell the entire story. NPCI’s clarification also points to a rise in higher-value person-to-merchant transactions. Payments above ₹2,000 accounted for 15.1% of total P2M transaction volume in financial year 2023, according to the information cited in the report. That share rose to 20.1% in the June quarter of financial year 2027. The figures indicate that the segment exposed to MDR is expanding, even though it remains smaller than the zero-MDR segment by volume.
This creates a difference between the number of transactions affected and the value of the payments potentially exposed to the charge. A smaller share of high-value payments can represent a substantial portion of the money moving through the system. The supplied material does not provide the total value of these transactions, so it does not establish the precise share of UPI payment value that will attract MDR. It does, however, show why the debate cannot be resolved only by stating that most transactions are below ₹2,000.
The institutional design also reveals how India’s digital payment infrastructure is being financed. UPI has been widely associated with low-friction payments for consumers and merchants. The MDR framework separates the customer’s payment experience from the underlying settlement cost. The customer may continue to see a simple UPI payment, while the merchant, acquiring bank, payment service provider or other participant handles the applicable service charge and tax treatment.
That separation makes the tax issue technically manageable but commercially significant. A merchant may not face a GST charge on the entire sale, but could still face a payment-processing cost when the transaction crosses the threshold. Whether that cost is absorbed by the merchant, passed through to customers or negotiated across the payment ecosystem is not established in the supplied material. The report does not state that merchants will be permitted to add a separate charge to customers, nor does it establish how every category of merchant will account for the fee.
The policy therefore has at least three distinct layers. The first is the transaction threshold: payments up to ₹2,000 remain at zero MDR, while payments above it enter the applicable framework. The second is the rate structure: a 0.4% MDR, capped at ₹300, with specific concessional treatment for selected sectors. The third is the tax and credit structure: GST is applied to MDR, and eligible registered businesses may claim input tax credit.
Each layer affects a different part of the urban economy. The threshold is most relevant to consumer behaviour and the payment choices available to small merchants. The rate is relevant to operating margins and payment acceptance costs. The input tax credit mechanism is relevant to formalisation and tax compliance. A merchant that is GST-registered and sells taxable goods may be able to offset the charge, while a business outside that structure may experience it as a direct expense.
The reported estimate of possible GST collections further indicates the scale of the fiscal question. Tax experts cited in the report estimate that GST collected on MDR could reach several thousand crore rupees annually. One estimate places potential gross collection at about ₹5,184 crore a year, based on merchant payments above ₹2,000 and a uniform 0.4% MDR. The report also warns that actual net revenue would depend on discounts, concessional MDR rates, transaction limits and input tax credit claimed by eligible businesses.
That qualification is important. The ₹5,184-crore figure is an estimate based on stated assumptions, not a confirmed collection outcome. The final amount would depend on the composition of transactions, the sectors receiving concessional treatment, the actual MDR charged and the extent to which tax credits reduce net liability. The figure should therefore be read as an indication of possible fiscal scale rather than a settled revenue forecast.
For policymakers, the challenge is to preserve the accessibility of digital payments while recognising that the payment system has different users and different cost capacities. Zero MDR for low-value payments protects the high-frequency transactions most closely associated with everyday commerce. At the same time, the growing share of higher-value P2M payments brings more formal payment services into the system and creates a taxable service-fee base.
For merchants, the practical issue will be less about whether GST is charged on a ₹10,000 sale and more about the accounting treatment of the MDR attached to that sale. The effect will vary with registration status, product category, monthly receipts and the payment route used. NPCI’s clarification reduces the risk of misunderstanding the tax base, but it does not eliminate the need for merchants to understand the fee structure and their eligibility for credit.
The evidence supplied so far confirms three points: GST is described as applying to MDR rather than the full UPI transaction value; payments up to ₹2,000 and certain low-income merchant thresholds remain outside MDR under NPCI’s explanation; and the share of higher-value P2M transactions is increasing. What remains uncertain is the precise value share of affected transactions, the distribution of the cost among payment-system participants and the eventual net GST collection after credits and concessions. Those are the indicators that will show whether the change remains a limited charge on higher-value digital payments or becomes a wider issue for India’s merchant economy.